

Highway No Longer Takes Toll on Bankruptcy
 The operators of Ontario’s Highway 407 Express Toll Route (ETR) can no longer arrange for vehicle permits to be withheld from bankrupt drivers, according to a recent Ontario’s Court of Appeal ruling.
A January 2nd Toronto Star article states, “A recent series of court battles have attempted to resolve a key question that pits federal legislation against provincial: if a driver doesn’t pay the 407ETR toll, should the province take away their licence?”
The provincial Highway 407 Act dictated that the answer was yes. If the drivers didn’t take care of their tolls then the highway company could contact the province, which would refuse to issue vehicle permits to the drivers until everything was paid up.
This would include people who were undergoing bankruptcy and sometimes owed tens of thousands of dollars to the toll highway. Feeling that this violated the “fresh start” principle of the Bankruptcy Insolvency Act (BIA), lawyers launched a class action suit on behalf of insolvent drivers denied vehicle licences despite being declared bankrupt.
“As a trustee we had to tell people that though their future discharge would legally erase the debt, they would probably still have to pay the 407ETR debt or at least make a settlement with them if they wanted to license their car,” explains Richard Killen, president and trustee with Richard Killen & Associates. “There was nothing illegal about the 407ETR accepting a ‘voluntary’ payment from a discharged bankrupt. The Ministry of Transportation would then receive a notice from the 407ETR that the debt was paid and a licence would be issued. The circular argument made any effort to solve the problem an exercise in futility. The MOT simply shrugged and tossed the ball over to the 407ETR.”
He adds, “It took years for the Federal Office of the Superintendent of Bankruptcy to involve itself, and even that was only after a bankrupt pushed this challenge through the lower courts. This appellate decision pretty well puts to rest the whole question. Now we are in a position to tell people when they consult us that their debt to the 407ETR is as dischargeable as their debt to Visa. This is news.”
Cure Your Holiday Hangover with Credit Free Fridays
 During the holiday season, the joy many of us feel is tempered by our dread at opening credit card invoices in January. Apparently we pay for our pleasures.
We will make New Year’s resolutions and vow to shed weight at the gym and through dieting. Why not put your budget on a diet, embracing the discipline of Credit Free Friday?
This is a movement espoused by personal finance gurus David Ramsey and Canada’s own Gail Vaz-Oxlade. The belt-tightening up here gained steam last year when the Canadian Federation of Independent Business (CFIB) and Vaz-Oxlade announced the launch of the Credit Free Friday campaign.
“Excessive use of credit cards, especially premium credit cards, contributes to escalating consumer debt and hurts small businesses,” explains its. “Credit Free Friday is a campaign that encourages Canadians to take a break from using their credit cards, one Friday at a time, by paying with cash or Interac Debit.”
The site also provides sobering credit card facts (the average Canadian now owes more than $27,000, and that doesn’t include mortgages), advice on how to get involved with Credit Free Fridays, a few debt stories and tools to help manage debt problems.
A New Problem for the Old
 While aging baby boomers aspire to a placid retirement, this dream is being threatened by a growing problem: senior debt. An August 2013 article in Financial Post says, for example, “A report provided [by] ratings agency Equifax Canada shows average debt for consumers aged 65 and over climbed 6.5 per cent over the past year, the biggest year-over-year increase in the period for any age group.”
Apparently Canadians 65 and older account for eight per cent of bankruptcies, up from six per cent five years ago. “There’s been an increase since 1987 in bankruptcy of people over 65 of 3,900 per cent, it’s just huge,” says Nadim Abdo, vice-president of consulting and analytical services at Equifax.
Some reasons for this alarming situation include:
- People are living longer, so may not have saved enough money to cover their entire retirement.
- Parents are bailing out debt-ridden adult children.
- Seniors are sinking too much money into real estate, lured by low interest rates and the prospect of high returns.
- Widows or widowers don’t change their spending habits after a spouse dies and their pension disappears.
The results of this rising problem is not only the anxiety of dealing with creditors but the increased risk of health problems, such as rising blood pressure and heart attacks, and passing estates to heirs that have to be placed into bankruptcy because of crushing debt.
Five Things You Should Know About Credit Cards
 Too often credit cards seem like easy money. Just hand it over to the clerk or type in the card number for your online purchase and, presto!, you have stuff. But you may pay to play. If you don’t take care of your credit card balance on time, you can get penalized with late fees and bad credit scores.
While most of us know this on some level, it’s worth the reminder. Canadians continue to fall further and further into debt, with their love of bank loans, car loans, lines of credit and credit cards leading the way. Last month the average Canadian consumer’s total debt rose $225 to $27,355 according to the latest analysis of credit trends by TransUnion.
So here’s five things you should know about the plastic plunderer in your pocket:
- Don’t Live Without Grace: When buying with a credit card you are basically taking out a loan, which means paying interest. Usually the interest is waived if you pay within a “grace” period. Check to see whether your card’s grace period is 30 days, 20 days or one of the lovely “specialty” cards that has no grace period at all.
- Minimum Payments Maximum Pain: What’s wrong with just paying the minimum balance cited on your credit card invoice? If you were to figure out how much time and money, in the form of interest payments, you would spend to pay off a balance with minimum payments, you would be staggered.
- Never Be Late: Not only does missing the deadline for a credit card payment carry a financial penalty, it may bump up your interest rate and damage your credit rating. Ouch!
- Dangers of Juggling: You might be tempted to transfer your balance to a credit card with a lower interest rate. This could be OK if you pay off the balance during the period the low rate is offered. If not, check the fine print, because you may wind up paying a higher rate than before.
- Doesn’t Advance Your Cause: Doing cash advances with a credit card at an ATM is not a good idea. Not only are you charged a high interest rate there is no grace period. As soon as the money leaves machine, the credit clock is ticking.
Surviving the End of the World
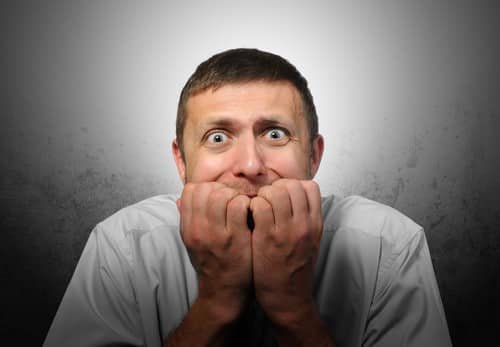 The fear is eating away your stomach lining. You can’t sleep. You can’t concentrate. You feel like a failure in the eyes of the world.
The envelopes of the unopened bills have changed to new ominous colours. The days you could juggle minimum payments between credit cards is coming to an end as you reach your limits. You stop answering the phone calls for fear of bill collectors . . . and then the phone stops working altogether.
Many people come to Toronto Licensed Insolvency Trustees gripped by the worst fear of their lives. They are looking at the end of their world, and who could be complacent in the face of that?
When people arrive at one of our offices for the first time, turning the handle of the front door feels as hard as moving a boulder. What our trustees try to convey at this meeting is that their visitors are not the first to have faced this situation. And while things might be dire, we are no longer a society that sends people to debtor prison. You can take concrete steps to deal with the crisis and begin the trip back to solvency and self-respect.
Of course, not all severe debt problems need to be dealt with by bankruptcy. But let’s assume you must face the worst. Does it mean that your world is over? No, absolutely not. While we cannot wave a magic wand and make everything go away, we can help you manage the process so that the road to recovery is seen clearly and followed sooner.
People ask if they will lose everything they have. No. Contrary to popular belief, you don’t lose all your assets when you go bankrupt. While there might be some things you have to give up, you will probably get to keep your furniture, personal effects, car and business tools.
What will stop the lawsuits and wage garnishees? some ask. A bankruptcy immediately stops anyone from suing or garnisheeing you, even the CRA. Only Family Responsibility Office Garnishees aren’t stopped.
Will my spouse and their property be affected by my bankruptcy? Probably not, except perhaps indirectly.
The above only touches on some of the issues a first free assessment covers. To get a full appraisal you need to come in and move the boulder on our front door. We guarantee that the knob will be a lot easier to turn on the way out.
Contact Richard Killen
FREE No Commitment Consultation
Contact us now for a fresh start!
“Serving Toronto & the GTA for over 25 years.”
Recent Blog Posts
- Why More Canadians Are Choosing Consumer Proposals for Debt Relief and Financial Recovery
- Consumer Proposal vs. Bankruptcy in Ontario: How Income and Assets Decide Your Best Route
- Are You Managing Debt or Just Surviving It? 10 Warning Signs It’s Time to Seek Debt Relief Solutions in the GTA
- Borrowing for Home Renovations in the GTA: Questions to Ask Before Taking on More Debt and How an LIT Can Help
- Back-to-School Expenses Are Adding Up: How to Prepare Without Going Into Debt Help Ontario