

Consumer Proposal vs. Bankruptcy in Ontario: How Income and Assets Decide Your Best Route
When debt starts piling up, figuring out what to do next can feel exhausting. If you’ve been searching online for clear guidance on consumer proposal vs bankruptcy Ontario, you’ve probably seen conflicting advice: “Keep everything you own with a Consumer Proposal!” or “Wipe your slate completely clean with Bankruptcy!”
The truth? Neither option is automatically “better” than the other. They are simply two different legal safety nets designed for different situations.
When evaluating your debt relief options in the GTA, choosing the right path isn’t about guessing—it boils down to three straightforward factors:
- How you repay the debt – Understanding repayment terms and schedules.
- What happens to your assets – Protecting your home, car, or savings.
- What a Licensed Insolvency Trustee (LIT) sees – How a professional evaluates your financial numbers.
Repaying the Debt: What Does the Monthly Routine Look Like?
The biggest difference between a Consumer Proposal and Bankruptcy comes down to how your monthly payments work.
Consumer Proposal: A Monthly Deal You Can Count On
If you’ve been wondering how does a consumer proposal work, it is simply a custom payoff plan negotiated with your creditors through a Trustee. You ask to pay back a realistic fraction of what you owe—often reducing your total debt by up to 80%—over a period of up to 5 years, with zero interest.
- Why people choose it: Your monthly payment is locked in from day one. If you get a raise, land a better job, or sell something valuable down the road, your payment stays exactly the same. For GTA residents with a reliable income or room to grow in their careers, this makes budgeting easy.
Bankruptcy: A Quick Exit Button
Bankruptcy is a formal legal process meant to clear away most unsecured debts when paying them back—even a small chunk—just isn’t realistic.
- Why people choose it: Speed and a clean slate. A first-time bankruptcy is often finished in as little as 9 months. Instead of negotiating a monthly payment plan, what you pay each month is set by standard government rules based on what you earn and how many people live in your household.
Your Assets: What Do You Get to Keep?
In high-cost areas like Toronto, Mississauga, or Brampton, keeping a house or car is usually top of mind. Understanding what assets can you keep in bankruptcy ontario helps clarify how each option treats what you own.
Consumer Proposal: Keep Everything
With a Consumer Proposal, you keep 100% of your assets. You do not give up your house, car, savings, or personal belongings to your creditors.
- The GTA Factor: If you own a home in the Greater Toronto Area, chances are you have built up significant home equity over time due to high local real estate values. Under Ontario law, bankruptcy only protects home equity up to a modest legal exemption limit—meaning high equity can put your home at risk of being refinanced or sold to pay creditors. A Consumer Proposal solves this problem. It allows GTA homeowners to keep 100% of their property. Instead of selling your home, your Licensed Insolvency Trustee negotiates a manageable monthly payment plan over up to 5 years that reflects what creditors would have received in a bankruptcy—giving you full protection of your home and equity.
Bankruptcy: What Is Protected vs. What Isn’t
Under Ontario law, bankruptcy is designed to protect the essential items you need to maintain a basic standard of living and continue working.
- What you keep (Exempt Assets):
- Clothing: Necessary personal apparel for you and your dependents.
- Household Basics: Everyday furniture and appliances up to statutory limits.
- Transportation: One primary motor vehicle up to the provincial equity threshold.
- Tools of the Trade: Equipment and tools required to earn an income in your trade or business.
- Retirement Savings: Your RRSPs, RRIFs, and DPSPs—except for any contributions made in the 12 months prior to filing.
- What might be sold (Non-Exempt Assets):
- High Home Equity: Equity that exceeds the provincial principal residence exemption.
- Luxury/Secondary Vehicles: Excess equity in primary vehicles or secondary leisure vehicles (e.g., boats, RVs).
- Non-Registered Investments: Savings held in TFSAs, non-registered stocks, or mutual funds.
The Two Main Factors: How Income & Equity Direct Your Path
If you are trying to figure out which path makes the most sense for you, you don’t have to guess or rely on general advice. When a Licensed Insolvency Trustee reviews your file, two main numbers dictate the best option: your household income and the equity in your property.
1. How Your Income Drives the Cost (Surplus Income Rules)
Every year, the Office of the Superintendent of Bankruptcy sets standard income guidelines for households of different sizes. This is the baseline amount of money a family is expected to need for basic living expenses like food, housing, utilities, and clothing.
If your household earns more than this official baseline, you exceed the surplus income threshold Ontario guidelines. Here is why that matters:
- In Bankruptcy: The law requires you to pay 50% of whatever income you make above that set government threshold into your bankruptcy estate each month.
- The Catch: If your surplus income averages more than $200 a month, your bankruptcy automatically extends from a standard 9-month process to a 21-month process, and your required monthly payment goes up.
- In a Consumer Proposal: Earning a solid income does not penalize you or extend your timeline. Instead, having steady surplus income makes you a strong candidate for a proposal. Your payment is fixed, so if you earn extra money through bonuses, promotions, or overtime, 100% of that extra money stays in your pocket.
2. How Much Your Property Is Worth (The Asset Equity Factor)
Equity is simply the market value of your property (like a home or car) minus what you still owe on it.
When you file a Consumer Proposal, your creditors have to vote on whether or not to accept your offer. To get a “yes” vote, your creditors need to see that your offer gives them a better deal than they would get if you filed for bankruptcy.
What does this look like in real life?
Imagine you own a home in Brampton with $40,000 in equity after mortgage payoff and sales costs.
- Scenario A (Bankruptcy): Under Ontario bankruptcy laws, home equity over $10,875 isn’t protected. The Trustee would generally need to unlock or realize that $40,000 in equity for your creditors—which could mean having to sell or refinance the home.
- Scenario B (Consumer Proposal): You keep your home completely intact. Instead of selling the home, your Trustee designs a proposal where you offer your creditors slightly more than $40,000 (say, $42,000) paid out in monthly installments over 5 years ($700/month).
| THE EQUITY BALANCE IN ACTION | |
| IF YOU FILED BANKRUPTCY… | IN A CONSUMER PROPOSAL… |
| Creditors get value from liquidating non-exempt equity. | You offer creditors a total sum equal to or slightly higher than that equity… |
| RESULT: Assets like home equity may need to be realized or sold. | RESULT: You keep 100% of your property and pay over up to 5 years. |
By balancing your income stability with your property value, an LIT can structure a Consumer Proposal that gives your creditors a fair offer while ensuring you protect the things you’ve worked hard to build.
The LIT Advantage: Your Navigational Partner in the GTA
Online debt calculators and generic advice can’t account for household nuances, tax liabilities, or creditor expectations.
A Licensed Insolvency Trustee (LIT) is the only professional in Canada authorized by the federal government to administer both Consumer Proposals and Bankruptcies.
How an LIT Works for You:
- Neutral Assessment: We conduct a comprehensive review of your debts, assets, family size, and income to calculate exact surplus income thresholds and equity figures.
- Transparent Options: We outline every available choice—including options outside insolvency—so you can make an informed decision.
- Legal Protection: Filing either option through an LIT immediately stops wage garnishments, halts collection calls, and freezes interest charges.
Take the First Step Toward Financial Clarity
You don’t have to figure out the right path on your own. Whether you’re balancing a mortgage, managing household expenses, or simply seeking relief from high-interest debts, an initial consultation provides complete clarity on your numbers and options.
Ready to explore your options?
Schedule a free, confidential consultation with one of our Licensed Insolvency Trustees today. We offer flexible virtual appointments and convenient office locations across the Greater Toronto Area—including Downtown Toronto, Mississauga, Scarborough, Brampton, and Markham.
Call us at 1-888-545-5365 or book online today.
Are You Managing Debt or Just Surviving It? 10 Warning Signs It’s Time to Seek Debt Relief Solutions in the GTA
In a region like the Greater Toronto Area, standard advice on how to pay off high-interest debt often falls flat. When high living costs and heavy monthly bills eat up every dollar you make, it is remarkably easy for your finances to slip into financial survival mode.
You are far from alone in facing these challenges. According to Statistics Canada, household debt reached 177.2% of disposable income in late 2025, meaning Canadian households owed approximately $1.77 for every dollar of disposable income earned. In a high-cost market like the GTA, this ratio shows how easily everyday living expenses can outpace earnings—causing debt to quietly compound over time rather than stemming from a single financial crisis.
Financial survival mode isn’t always chaotic—often, it looks quiet and organized. You pay your bills on time, keep food on the table, and maintain a respectable credit score. But under the surface, you aren’t actually reducing what you owe—you are simply on a high-speed financial treadmill, using credit to tread water.
Recognizing the key signs you need debt help isn’t a sign of failure. It is the critical first step toward protecting your hard-earned assets and regaining peace of mind. Here are 10 subtle red flags that indicate it’s time to seek professional guidance—and why acting early changes everything.
Category A: Subtle Lifestyle & Necessity Triggers
1. Credit Rules the Grocery Aisle
Using a credit card for daily living expenses isn’t inherently bad, but relying on credit or Buy-Now-Pay-Later (BNPL) services to cover basics—like groceries, transit, or utilities—because your bank account is empty is a major red flag. When essential monthly living costs depend on borrowed money, your cash flow is overextended.
2. You’re Trapped in the “Minimum Payment” Loop
You faithfully pay your credit card bills every month, but when the next statement arrives, the total balance has barely nudged. If 80% or more of your monthly payment goes directly toward interest, you are paying for the past rather than funding your future.
3. The Credit Card Shuffle
If you find yourself using one credit card or line of credit to make payments on another, or constantly moving balances between 0% promotional cards just to buy a few months of breathing room, you are managing debt logistics rather than solving the underlying problem.
Category B: Cash-Flow & Asset Strain
4. Maxed-Out Safety Nets
Your emergency savings account is sitting at zero, and your overdraft protection or line of credit is tapped to its upper limit. Without a cushion, a single unexpected expense—like a car repair or dental emergency—can trigger a severe financial tailspin.
5. Dependency on Overtime or Side Income Just to Stay Afloat
Relying on variable income—such as overtime hours, bonuses, or side hustles—just to meet your fixed monthly debt obligations puts you in a fragile position. If those extra hours dry up, your budget immediately breaks.
6. Draining Home Equity to Pay Off Consumer Debt
With GTA property values, tapping into a Home Equity Line of Credit (HELOC) or refinancing a mortgage to cover credit card debt is a tempting fix. However, if the underlying cash-flow deficit isn’t fixed, consumer debt often creeps back within a couple of years—leaving you with both credit card debt and a much larger mortgage.
Category C: Escalation & Emotional Burden
7. “Robbing Peter to Pay Paul”
Each month becomes a stressful puzzle: choosing which utility bill to skip or pay late just to keep aggressive creditors off your back. In a high-cost area like the GTA, juggling payments this way isn’t a long-term plan—it is a temporary patch that triggers extra fees, hurts your credit, and creates a perpetual cash-flow emergency.
8. Active Avoidance: Ignoring Creditors and Mail
You’ve turned off the noise by ignoring unknown callers and letting mail stack up. This is a coping mechanism driven by dread—you are avoiding the creditors and refusing to look at the reality of what you owe.
9. Interpersonal Deception: Hiding the Truth from Loved Ones
This moves from avoiding creditors to actively hiding the truth from the people in your home. Driven by shame, you intercept mail before a partner sees it, downplay balances, or hide purchases to maintain the illusion that everything is under control.
10. “Financial Insomnia”
Debt stress isn’t just a spreadsheet problem; it manifests physically. If worrying about money keeps you awake at night, impacts your job performance, or damages your personal relationships, the emotional cost of your debt has exceeded what anyone should bear.
Quick Self-Assessment: Are You in Financial Survival Mode?
Ask yourself these five simple questions:
- Daily Living: Are you using credit cards or BNPL services to buy essentials like groceries, gas, or utilities?
- Progress: Have your total debt balances stayed the same or grown over the last 6 to 12 months despite making payments?
- Income Strain: Are you relying on overtime, side hustles, or home equity just to cover basic monthly obligations?
- Bill Logistics: Do you find yourself shuffling funds or delaying certain bills just to satisfy more aggressive lenders?
- Mental Toll: Does thinking about your debt, opening mail, or answering unknown calls cause noticeable anxiety?
Scoring Your Results:
- 1 “Yes” answer : You are on the edge—now is the best time to adjust your budget before things escalate.
- 2 or more “Yes” answers: Your finances are operating in survival mode. It’s time to explore realistic debt relief solutions in the GTA and talk to a Licensed Insolvency Trustee.
Why Spotting Warning Signs Early Changes Everything
Postponing action rarely makes debt disappear—it usually just consumes the assets you could have protected. Waiting too long often forces people to drain locked-in RRSPs, sell personal assets, or exhaust home equity that federal and provincial laws might otherwise safeguard.
Seeking professional help early means you retain more options and keep greater control over your financial roadmap.
How a Licensed Insolvency Trustee (LIT) Helps
Licensed Insolvency Trustees (LITs) are the only debt relief professionals in Canada regulated by the federal government. Unlike unregulated debt settlement agencies or credit counselors, an LIT evaluates your situation with complete legal transparency and can offer legally binding solutions.
When you sit down with an LIT, they look at your full financial picture to determine the right path forward:
- Consumer Proposal: A formal, legally binding agreement negotiated with your creditors to pay back a percentage of what you owe over up to five years. Filing a consumer proposal in Ontario freezes interest immediately, stops collection calls, and lets you keep all your assets—including home equity, vehicles, and investments.
- Bankruptcy: A legal process designed to discharge eligible debt quickly (often in as little as 9 months for a first filing), offering a true fresh start when debt drastically outpaces your ability to pay.
Whether you need targeted credit card debt relief in Toronto or a complete financial reset, an LIT performs a personalized assessment based on your income, expenses, and asset equity before you make any decisions.
Take the First Step to a Clearer Path Forward
If you recognize your financial situation in any of these warning signs, you don’t have to navigate it alone or stay in survival mode forever.
With convenient office locations across Toronto, Mississauga, Brampton, and the greater GTA, our team of Licensed Insolvency Trustees is here to help you move from surviving to thriving.
Contact us today to schedule a free initial debt consultation in the GTA. We’ll calculate your numbers, explain your rights under Canadian law, and help you choose the debt solution that protects your financial future.
Holiday Debt Relief Ontario: Where to Get Help Now
Feeling the pinch after the holidays? You’re not alone. Each year, countless families search for holiday debt relief in Ontario after facing the financial aftermath of seasonal spending. Whether it’s credit card balances, gift expenses, or unexpected costs, the post-holiday reality can be overwhelming — but you don’t have to navigate it alone.
There are proven, practical solutions available right here in Ontario. From practical budgeting to professional support, there are clear, manageable steps you can take to regain control of your finances and your peace of mind.
Start With Smart Budgeting Tips After Holidays
Regaining control over your finances starts with an honest, structured budget. The goal is to get clear about what you owe, what you earn, and how you can allocate your resources most effectively.
Here are some essential budgeting tips after holidays to kick things off:
- Track your spending: Review all your December and early January transactions to see where your money actually went. Use apps like YNAB, KOHO, Goodbudget or simply use a spreadsheet.
- Separate wants from needs: Focus on covering essentials first — rent/mortgage, groceries, utilities — and trim unnecessary expenses.
- Set realistic repayment goals: Break large debts into manageable monthly targets. Avoid setting goals that will leave you financially strained.
- Create a ‘holiday recovery’ category in your budget: Set aside money specifically for paying down any seasonal debt.
Most importantly, don’t feel discouraged if you’re not where you want to be. A budget isn’t about restriction — it’s about direction.
Streamline Payments With Debt Consolidation Options
If you’re juggling multiple debts with high interest rates, exploring debt consolidation options can make a huge difference. It’s not a magic fix — but it simplifies your financial life and can reduce the total interest you’ll pay.
Some common consolidation methods in Ontario include:
- Personal loans: Borrow a fixed amount from your bank or credit union to pay off existing debts, then repay the loan with a single monthly payment.
- Balance transfer credit cards: Move high-interest credit card balances to a card offering a 0% introductory rate for 6–12 months. Just be sure you have a plan to pay it off before the rate expires.
- Home equity lines of credit (HELOCs): If you own property, you may qualify for a HELOC with much lower interest than credit cards.
Debt consolidation doesn’t reduce the amount you owe, but it helps make repayment more manageable by reducing complexity and potentially lowering your interest rate.
When to Consider a Consumer Proposal Ontario
If your debt load is more than you can realistically repay, filing a consumer proposal in Ontario may offer much-needed breathing room. A consumer proposal is a legally binding agreement filed by a Licensed Insolvency Trustee (LIT) that allows you to settle your unsecured debts for less than you owe — without interest and without declaring bankruptcy.
Key advantages include:
- You keep your assets – Unlike bankruptcy, you don’t risk losing your car, home, or savings.
- Monthly payments are fixed – No surprises or increases in your repayment terms.
- Collection calls stop – As soon as the proposal is filed, all creditor actions — including lawsuits and wage garnishments — are put on hold.
- Improved credit over time – A consumer proposal impacts your credit, but less severely than bankruptcy, and you can begin rebuilding sooner.
This option is ideal for those with regular income who can repay a portion of what they owe, but need legal protection and lower payments.
What a Licensed Insolvency Trustee Ontario Can Do for You
A Licensed Insolvency Trustee is your go-to professional when debt becomes unmanageable. LITs are federally licensed and regulated, and they’re the only professionals legally allowed to administer consumer proposals and bankruptcies in Canada.
Here’s how an LIT can help:
- Assess your financial situation – LITs perform a full review of your income, debt, assets, and expenses to recommend the best course of action.
- Present all your options – They’ll explain not just formal solutions like proposals or bankruptcy, but also informal ones like budgeting advice or consolidation.
- Handle paperwork and negotiations – LITs communicate directly with your creditors and ensure your legal rights are protected throughout the process.
- Offer free initial consultations – You can speak to an LIT without cost or commitment, giving you the chance to understand your options before making any decisions.
Choosing to work with an LIT provides peace of mind, knowing you’re getting unbiased, professional support from someone who is legally and ethically accountable.
Practical Advice on How to Manage Holiday Debt
Feeling overwhelmed is normal, but taking small, consistent steps can make a big difference. Managing holiday debt doesn’t require drastic measures—it’s about building momentum and staying committed.
Try these practical strategies:
- Pick a repayment strategy –
- Snowball method – Pay off the smallest debt first to gain momentum.
- Avalanche method – Pay off the highest interest debt first to save money.
- Automate your payments – Set up automatic withdrawals so you don’t miss due dates.
- Cut back temporarily – Pause subscriptions or reduce discretionary spending while you focus on repayment.
- Track your wins – Keep a visible list of debts shrinking — progress is powerful.
Managing debt successfully means staying consistent and adjusting your strategy if your circumstances change.
Tap Into Ontario Debt Help Services
If you’re unsure where to get help with holiday debt in Ontario, don’t worry — there are reputable, accessible services available to guide you. Many non-profit and government-supported organizations offer financial education, debt relief programs, and connections to Licensed Insolvency Trustees or certified credit counselors.
These resources can help you:
- Explore your debt relief options without judgment
- Understand your rights as a debtor and the legal protections available to you
- Get professional advice tailored to your income and lifestyle
Start by visiting the Government of Canada’s list of licensed trustees or contacting a local credit counselling agency for support. Look for organizations that are accredited, transparent about fees, and focused on long-term solutions—not just quick fixes.
Is Credit Counselling Ontario Right for You?
One of the most underused resources is credit counselling Ontario, typically offered by accredited non-profits. These services are ideal for people who need more structured help in organizing their finances than DIY budgeting but aren’t necessarily ready for legal debt solutions like a consumer proposal.
These agencies can help you create a realistic repayment plan, negotiate lower interest rates, and stay accountable with monthly check-ins. Just be sure to choose a non-profit, accredited agency. Some for-profit companies charge high fees for services that should be free or low-cost.
Credit counselling services can include:
- Budgeting workshops and one-on-one coaching
- Debt management plans negotiated with your creditors
- Educational tools to help prevent future financial hardship
Because they work in your best interest — not your creditors’ — these organizations are a trustworthy place to start if you’re feeling overwhelmed but not in crisis.
Try Flexible Debt Repayment Strategies
Not every strategy fits every person. The best debt repayment strategies are the ones that match your financial habits and mental approach.
Consider:
- Biweekly payments – Splitting your monthly payments into two can reduce interest and make budgeting easier.
- Cash envelope systems – Helps limit overspending in certain categories like dining out or shopping.
- Using extra income wisely – Apply any tax refunds, bonuses, or side hustle income directly to your highest-priority debts.
Flexibility is key — choose methods that feel manageable so you’re more likely to stay on track.
Tips to Get Out of Debt After Holidays With Less Stress
Looking to get out of debt after holidays without feeling overwhelmed? Focus on reducing stress while taking steady action.
Here are some ways to ease the burden:
- Prioritize self-care – Financial stress is real — don’t neglect your mental health.
- Be honest with loved ones – If you’re cutting back on expenses, communicate it openly. Most people will understand.
- Set realistic timelines – Debt repayment takes time, especially if you’re balancing other responsibilities.
- Celebrate progress – Each paid-off account or milestone is a step toward freedom — acknowledge and reward yourself for it.
Patience, persistence, and self-compassion are your best allies on the road to financial recovery.
Specialized Holiday Credit Card Debt Solutions
Credit cards are usually the culprit behind holiday overspending. If you’re struggling with high balances, there are ways to reduce the burden and regain control.
Consider these solutions:
- Ask your lender for a lower interest rate or hardship program
- Transfer your balance to a lower-rate card (watch for fees and terms)
- Use a debt management plan through a non-profit credit counselling agency
- Avoid minimum payments—they prolong debt and increase interest costs
The key is to act early — the longer you wait, the more interest builds up and limits your options.
Conclusion: You’re Not Alone — and Relief Is Possible
Debt doesn’t have to define your new year. With the right tools, support, and mindset, you can turn the page on seasonal overspending and start fresh. Whether you choose to budget smarter, consolidate, propose a settlement, or speak with a professional, the path to holiday debt relief in Ontario is within reach. Take the first step today — your future self will thank you.
Ready to Take the First Step?
If you’re feeling overwhelmed by post-holiday debt and don’t know where to start, a Licensed Insolvency Trustee can help. LITs are Canada’s only federally regulated debt professionals — and their advice is confidential, judgment-free, and tailored to your unique situation.
Contact a Licensed Insolvency Trustee at Richard Killen & Associates to book your free consultation and explore your options for lasting financial relief.
When Holiday Loan Debt Turns Into Long-Term Trouble
Holiday loan debt can sneak up on even the most budget-conscious Ontarians. What starts as a manageable monthly payment can become a burden when interest accumulates or when unexpected life expenses arise. Many Ontarians find themselves caught in a cycle of making minimum payments, rolling over balances, or even borrowing more just to keep up. This can lead to chronic financial stress and damage to credit health over time.
If you’ve already borrowed and are now facing the consequences, you’re not alone. Support is available to help you understand your options, regain control, and move forward with confidence
Understanding How Holiday Loans Lead to Long-Term Debt
The long-term effects of holiday loans usually stem from the mismatch between short-term joy and long-term repayment obligations. Many Ontarians take out personal loans Ontario or use credit cards during the holidays, assuming they’ll pay them off quickly. But high interest rates, unexpected expenses, and limited income flexibility can turn a manageable balance into a persistent problem.
Here’s how it happens:
- Deferred payments or promotional interest rates may expire, leading to sudden spikes in monthly costs.
- Minimum payments stretch the debt over years, especially if you’re only covering interest.
- Multiple loans—including payday advances or credit card cash withdrawals—can compound the issue, making it harder to track and manage.
Holiday borrowing consequences aren’t just financial. They can affect your credit score, increase stress, and limit your ability to save or invest in the future.
What Ontarians Should Know About Holiday Loans and Debt
Holiday loan debt isn’t just about numbers—it’s about understanding your rights, responsibilities, and available resources. Ontario offers several consumer protection measures and support programs that can help borrowers navigate post-holiday financial strain.
- Ontario consumer protection loans are regulated to ensure transparency in terms and conditions. Always review the fine print before signing.
- Ontario debt support programs may offer free credit counselling, budgeting workshops, or referrals to financial advisors.
- Ontario debt help is available through community organizations, financial institutions, and licensed professionals.
If you’re unsure where to start, consider speaking with a licensed insolvency trustee Ontario. These federally regulated professionals can assess your financial situation, explain your options, and help you choose the best path forward—whether that’s budgeting, debt consolidation Ontario, or a formal insolvency process.
Steps to Take If Your Holiday Loan Turns Into Long-Term Debt
If you’re already feeling the pinch, don’t panic. There are practical steps you can take for managing holiday loan debt and prevent it from spiraling further.
1. Assess Your Current Financial Picture
Start by listing all your debts, including balances, interest rates, and payment due dates. This gives you a clear view of what you owe and helps identify which debts are costing you the most.
2. Prioritize Repayment
Use targeted strategies like the snowball method (paying off the smallest debts first) or the avalanche method (tackling the highest interest rates first). These approaches can build momentum and reduce overall costs.
3. Explore Holiday loan repayment tips
- Set up automatic payments to avoid late fees.
- Allocate windfalls (like tax refunds or bonuses) toward your loan.
- Cut non-essential expenses and redirect those funds to debt repayment.
4. Consider Debt consolidation Ontario
If you’re juggling multiple loans, consolidating them into a single lower-interest payment can simplify your finances and reduce stress. Banks, credit unions, and licensed insolvency trustees can help you explore this route.
5. Seek Professional Advice
A licensed insolvency trustee Ontario can help you understand whether a consumer proposal or bankruptcy is appropriate. These are serious steps, but they can offer relief and a fresh start when other options aren’t enough.
Alternative Approaches and Preventative Measures
Managing holiday loan debt isn’t just about reacting—it’s about planning ahead and making informed choices. Here are some preventative strategies and alternatives to borrowing:
Build a Holiday Budget
- Set spending limits for gifts, travel, and entertainment. Use cash or debit to avoid accumulating new debt.
Use Savings or Sinking Funds
- Start saving early in the year by setting aside a small amount each month. By December, you’ll have a dedicated holiday fund.
Explore Non-Monetary Gifts
- Homemade items, experiences, or acts of service can be just as meaningful—and far less expensive—than store-bought presents.
Learn What To Do After Taking a Holiday Loan
- If borrowing is unavoidable, make a repayment plan before you spend. Know your interest rate, monthly obligations, and how long it will take to pay off the loan.
Tap Into Debt help in Ontario
- Whether you need budgeting advice or emotional support, don’t hesitate to reach out. Many organizations offer free or low-cost services to help you stay on track.
Ontario Payday Loan Alternatives
- Payday loans are often marketed as fast, easy cash solutions, but they come with sky-high interest rates and fees that can trap borrowers in a cycle of debt. Instead of turning to these risky products, consider Ontario payday loan alternatives such as:
- Credit union small-dollar loans
- Employer payroll advances
- Community loan programs
- Borrowing from trusted sources
These alternatives offer safer, more sustainable ways to manage short-term financial needs without the high costs and risks associated with payday loans.
How To Get Out Of Holiday Loan Debt
Getting back on track financially after the holidays requires a mix of discipline, strategy, and support. It may feel overwhelming at first, but even small steps can lead to meaningful progress. Here’s a roadmap:
- Track your spending and identify areas to cut back.
- Increase your income through side gigs, overtime, or selling unused items.
- Negotiate with lenders for lower interest rates or extended terms.
- Use Ontario debt help resources to access counselling or financial planning.
- Consult a licensed insolvency trustee Ontario if your debt is unmanageable—they can guide you through legal options that protect your assets and dignity.
Final Thoughts: Take Control Before Holiday Loan Debt Controls You
Seasonal spending can leave a mark, but getting back on track is possible with the right mindset and support. Ontarians have access to a wide range of resources—from budgeting help and community programs to expert advice from licensed insolvency trustees. If you’re trying to make sense of your situation, exploring safer borrowing options, or simply need a fresh start, you’re not alone—and there’s help out there.
Whether it’s tweaking your budget, consolidating what you owe, or speaking with a licensed insolvency trustee in Ontario, every step forward counts. What was meant to bring joy shouldn’t leave you stressed for months to come—and holiday loan debt doesn’t have to follow you all year.
Ready to Take Back Control?
Don’t let seasonal spending shape your financial future. Whether you need budgeting support, debt consolidation advice, or professional guidance from a licensed insolvency trustee, help is available.
Let’s make sure holiday loan debt doesn’t shape your year — reach out and take the first step.
Richard Killen’s Christmas Message 2019
December is a very exciting and interesting time of year. From the official beginning of Winter to the various religious celebrations, such as Christmas and Hanukkah. It’s also a time for some philosophical pondering; reviewing the year past and formulating our resolutions for the coming year. Yes, December can be a very important month. It certainly is a good time to appreciate all the good things we are given, especially when they occur through no effort of our own.
True, not everything that happens to us is positive and easy to take. Everyone has the challenge of dealing with negative things like health problems and all the other personal trials life throws at us. Sometimes it feels like that’s all there is. But it isn’t, is it?
In the book I wrote, The Glass Is Half Full, I try to make the point that no matter how difficult our problems and challenges, the attitude with which we face them goes a long way to getting us through it and even turning these things around. Most importantly, we cannot let the bade things that happen to us define how we see ourselves.
I can’t think of a more valuable way to wind up the year. Maybe that’s why Christmas and Hanukkah take place at this time. For thousands of years these religious celebrations, and their cousins in other faiths, remind us of all the positive gifts life provides and how we should never take any of it for granted. They also encourage us to believe that facing up to our daily toil and turmoil courageously pays off for us in the end. That’s something we owe to ourselves and to those we love.
So with that thought, I’ll which all of you a very Merry Christmas and Happy Hanukkah and hope that you and yours are blessed with good health and happiness throughout 2020.
How to Save Money with Credit Cards
Many of us abuse the use of our credit cards and often end up in debt. However, if you can use the plastic in a responsible manner, you can actually save money with credit cards, and are often better off using them rather than paying in cash.
Here are some money saving strategies you can take advantage of to get the most out of your credit cards.
Rewards and Points
When you have a credit card that earns points, you can earn as much as five points for every dollar you spend. There are also several occasions when companies will offer special three-month promo periods where you can earn double or triple the usual amount of points. When you reach a certain point threshold, you can redeem your points by buying items direct from the credit card company’s rewards catalog or exchange those points for hotel stays, merchandise, gas, shopping vouchers or lifestyle experiences like concert tickets, movie tickets, fitness trackers and spa treatments.
The trick is to find the right rewards card that best fits with your spending pattern. For example, if you patronize a particular brand of clothing, gas station, hotel chain or airline, you can earn points and enjoy rewards faster. In this way, you get to Save money with credit cards in exchange for points and rewards and enjoy some really great perks — which if you add everything up is basically more beneficial than if you paid outright with cash.
Frequent-Flyer Miles
With travel rewards credit cards, you would rack up miles every time you book a flight with a specific airline. When you have accumulated enough frequent-flyer miles, you can redeem these miles for airline tickets, special airline discounts, companion tickets, hotel room discounts and other perks such as rental cars, use of airport lounges, cruises, trip cancellation insurance, trip delay reimbursement, lost luggage reimbursement and other reward options. Now that’s some very valuable mileage with huge savings for you! If you travel frequently – as in a lot – this could be a very valuable credit card reward for you. It goes without saying that if you barely ever travel, this is not the type of credit card for you.
Cash Back
Cashback credit cards are great because you can literally earn cash back every time you make a purchase on your credit card. The cashback is credited back to you on your monthly bill. When you check your next monthly statement, you can see the cashback offsetted on the month’s credit card bill. Some cards offer 2%, 3% or even as much as 6% cash back on selected purchases. There are some cards that offer an even higher rate of cash back but requires you to deposit the cash reward directly into an investment account.
With a cash back card, you can earn rebates mostly on dining, groceries, gas, food delivery, for shopping at specific stores. This lets you save money with credit cards on essentials like food, fuel, groceries and other daily necessities. However, cash back cards require a minimum spend each month before you can start earning cashback and they set a limit to how much cashback you can earn per month. If you’re confident you can hit the minimum monthly spend without hurting your budget, then the cashback reward may be worth it to help you save money on groceries, dining, petrol and other essentials every month.
Consolidate your credit card debt carefully
If you have high credit card debt , you can transfer your credit card balances to help you pay off debt. A balance transfer card offers a 0% or a low APR on the amount that is moved over, but only for a limited introductory period. To make sure you save money on this strategy, you need to be able to pay off the entire debt balance before the promotional rate period is over, in order to avoid any increase in the card rate. You can still save money whether the new card offers a 0% or low APR, and in the end it may still be worth doing a balance transfer because essentially the new balance transfer card carries a much lower APR than your old credit card. Calculate everything carefully. It would help a lot if you do a cost benefit analysis so you can take into account all costs and charges, like if you’ll be charged a balance transfer fee if you do the switch.
It’s impossible to get into debt trouble if you know how to use credit cards to your advantage. In fact, there have been many instances where the credit savvy can even save money with credit cards and use them in the most favorable way. They are a very handy tool to have in your life and if you are careful about how you manage your spending when using credit cards you can benefit a lot from all the perks they offer without damaging your credit and putting yourself in debt trouble.
2018 INSOLVENCY & RESTRUCTURING EXCHANGE
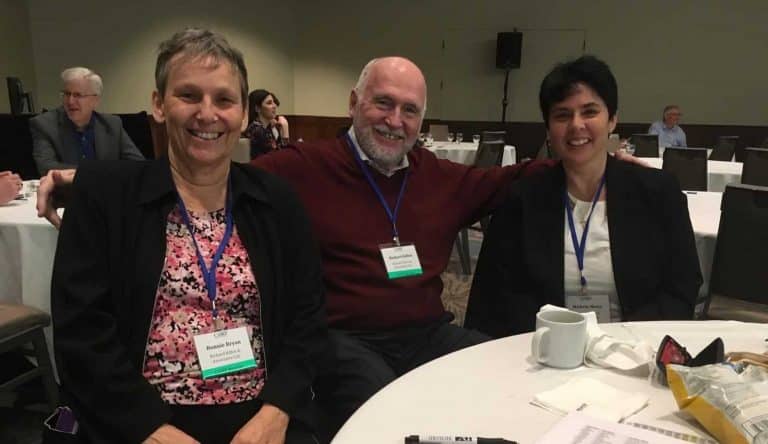
On October 26, 2018, Richard Killen, Bonnie Bryan and Michele Meitz attended the 3rd annual 2018 Insolvency & Restructuring Exchange in Toronto.
This is the Canadian Association of Insolvency and Restructuring Professionals (CAIRP) largest one day event of 2018. Almost ninety percent of Licensed Insolvency Trustees, licensed under Canada’s Bankruptcy and Insolvency Act are members of CAIRP.
CAIRP was created as a non-profit corporation in 1979 to advocate a fair, transparent and effective system of insolvency/restructuring administration throughout Canada.
This event is the best place for professionals from consumer and corporate restructuring practices to network and learn together.
We were glad to get the opportunity to meet and hear from fellow CAIRP members, lawyers, members of the judiciary, lenders and government officials as part of the days events.

Is A Payday Loan A Good Idea?

In this video, Richard Killen, a Licensed Insolvency Trustee in Bankruptcy Scarborough talks about whether a Payday loan is worth considering.
I guess one can say that going into debt, any kind of debt, is hardly ever a good idea. Usually, the cost of the debt outweighs whatever benefits you may get from borrowing the money. However, sometimes debts make a good case for making some worthwhile. For instance, is a mortgage worthwhile? Because you borrow a large amount of money for buying a house, you are going to pay back that money with interest but the house will appreciate in value. And over time that appreciation more than outweighs the cost of the debt. Maybe that kind of debt is a good idea.
Ultimately, it always boils down to whether the cost too much and how much is the cost? Now there is going to be interest on any loan and that is what you must consider. Now, unfortunately, Payday loans are on the high end of all interest calculations so one can say that it is tough to say if a Payday loan is worth it.
If a Payday loan is a part of your coping with bills, you should consider having a consultation with one of our trustees. It may be the most stress relieving call you make this year.
The Role of a Licensed Insolvency Trustee in Mississauga
The role of a Licensed Insolvency Trustee in bankruptcy Mississauga is critical in helping consumers who choose to go through the process of filing for bankruptcy to solve their overwhelming debt problems. Not only do they play a very big part in helping to minimize confusion, but they are present from beginning to end to make sure that every step of the process gets done as quickly and efficiently as possible.
Licensed Insolvency Trustees (LITs) are the only professionals licensed by the Federal Government of Canada to provide debtor information and advice to individuals and businesses with debt problems to help them make informed choices to deal with their financial difficulties. In addition, they are the only ones permitted by law to provide and perform debt restructuring services under the Bankruptcy & insolvency Act (BIA).
Licensed Insolvency Trustees in bankruptcy Mississauga were previously called bankruptcy trustees, or trustees in bankruptcy. The Office of the Superintendent of Bankruptcy Canada has recently changed their designation from bankruptcy trustee to Licensed Insolvency Trustee (LIT) in order to clearly differentiate them from debt consultants who are not licensed by the federal government to provide debt services.
The new designation is important to help eliminate any confusion or doubt among consumers about the legitimacy of LIT’s to provide government programs to eliminate debt. When dealing with a Licensed Insolvency Trustee, consumers are protected in three ways:
The Canadian government regulates the insolvency profession and ensures that Trustees are efficient and effective in complying with the insolvency process.
The Code of Ethics for Trustees establishes a standard for services that they are required to provide to a business or individual who has filed for bankruptcy.
The laws regulating the insolvency process makes sure that both the debtor’s rights and the creditor’s rights are respected.
In Mississauga, a Licensed Insolvency Trustee can provide a wide range of debt management solutions, including consumer proposals, loan consolidations, and bankruptcies. Insolvency Trustees are the most highly trained and educated debt experts that you can talk to. In most cases, trustees have obtained a university degree and most of them hold an accounting designation. For licensing, all trustees are required to complete a three-year bankruptcy and law course, pass a comprehensive oral examination, and undergo background investigation by the federal and national police force of Canada (the Royal Canadian Mounted Police). Only trustees who are licensed by the Office of the Superintendent of Bankruptcy Canada (OSB) can hold the designation of Licensed Insolvency Trustees.
Their role as debt professionals include the following:
- Provide free initial consultation to review your financial situation
- Explain to you in detail all your debt relief options, not just bankruptcy
- Recommend the best debt management solution that is best to your situation, which may or may not include any type of insolvency solution provided by the Bankruptcy & Insolvency Act
- Administer consumer proposals and bankruptcies and manage assets held in trust
- Gather all vital information to file the necessary documents and start insolvency proceedings
- Notify your creditors, accept and review all claims and administer the rules of the process
- Apply for your discharge or completion certificate once you’ve completed all your duties
- Ensure that everyone complies with their duties and responsibilities under the law.
If you are deep in debt and are getting harassed by non-stop collection calls and wage garnishments, consulting with a trustee is the most risk-free and inexpensive option you can take towards the right direction. A Licensed Insolvency Trustee in Mississauga can help you determine which debt relief option is best for you and your family so you can be on the road towards a debt free life.
Bankruptcy Counselors Toronto vs Licensed Insolvency Trustee
It almost sounds funny, doesn’t it? Bankruptcy Counselors Toronto – somebody who counsels people, presumably in Toronto, on how to go bankrupt? Perhaps the term is misleading? I think so. Real Bankruptcy Counselors, in Toronto or elsewhere, don’t counsel people to go bankrupt. In fact a Bankruptcy Counselor would probably spend more time trying to figure out how the person seeking advice could stay out of bankruptcy rather than go in it.
The term Bankruptcy Counselor itself is probably incorrect, at least in terms of the title itself. There are no Bankruptcy Counselors in that sense. What we do have are Licensed Insolvency Trustees in bankruptcy, such as Richard Killen & Associates Ltd., who are Federally licensed to administer the legal process called bankruptcy, along with other processes under the Bankruptcy and Insolvency Act called proposals and Consumer Proposals.
But a Trustee (it’s quite a mouthful to keep saying Licensed Insolvency Trustee when you are writing an article) is uniquely placed to talk to a person in debt trouble about bankruptcy, or a consumer proposal, as an option to deal with their debt problems. The Trustee can explain in detail how they work, how they might apply to that person’s situation, what the short term, medium term and long term practical advantages and disadvantages are. What effect they may have on all kinds of practical situations such as employment, bonding, mortgage renewals, and so forth. There are so many questions and so many areas of concern that people have when they are trying to solve their debt problems.
Let’s face it. Nobody actually wants to go bankrupt and making a consumer proposal is not much higher on a person’s to do list, is it? And let’s face something else. Though nobody wants debt trouble, it does happen. In today’s world of relatively easy access to consumer credit such as credit cards and lines of credit, not to mention mortgages and car loans, is it any wonder people get into debt trouble. This is not to say that we are not responsible for our actions, but not everyone can live every moment of their life within the proper bounds of prudence and coldly logical decision-making. Being human emotions come into play and do make some financial decisions without properly thinking it through. Later if something bad happens, like losing a job or coming down with an injury or an illness, what is a person supposed to do?
The answer, of course, is to do the best they can. That’s what most people do.- the best they can. But, if things go from bad to worse, there will come a time when the best they can is no longer good enough for their creditors, who simply want to get paid. When it gets to that point, there are not that many options available. In fact, depending on the severity of the trouble (How far behind you are with your payments? Are creditors threatening legal action?) there may only be one way that the person can maintain some control over his or her situation: use the Bankruptcy and Insolvency Act.
But using the solutions provided by a federal law is not something you should go into on a wing and a prayer. A little information might be in order and this information will have to come from someone who knows all sides of it. That is what the Licensed Insolvency Trustee (I used the whole title here so I could explain it) is supposed to be – the go to guy. Let’s look at what the title means and how it might relate to the term Bankruptcy Counselors Toronto.
“Licensed” simply refers to the fact that the Federal government, through the agency of the Office of the Superintendent of Bankruptcy, is mandated by law to oversee the administration of each and every bankruptcy and proposal filed in Canada. The law though says that a Trustee must be appointed to actually do the administration of each bankruptcy or proposal. So, the OSB determines who is qualified to be a Trustee through a series of investigation and heavy-duty testing and then licences those people it deems qualified to handle the job. That’s when they issue a licence.
“Insolvency” refers to the fact that this Trustee’s licence is specifically intended to relate to matters covered by the Bankruptcy and Insolvency Act. Let’s face it, the term trustee is used far and wide. For instance there are school trustees, who I am sure would not want to be confused with Insolvency Trustees. So the word Insolvency is stuck right in the middle to make it clear that these individuals are qualified specifically in that area and that they have been tested as to their ability to provide that service.
“Trustee” has a very broad meaning. The dictionary says a Trustee is a person given powers of administration over property and is legally bound to administer it solely for the purposes specified, in this case by the Bankruptcy and Insolvency Act. So in English that would appear to mean that a Trustee is responsible to administer the bankruptcy (and proposal) process for the purposes intended. Though that might cover a lot of ground, advising people about Bankruptcy or Proposals would certainly fall within that sphere.
All of which brings us back to the term Bankruptcy Counselor Toronto. If you are in debt trouble, facing a financial crisis, and you realize the fact, what can you do about it?
The first thing I think any rational person would do is get information, maybe advice. You can ask relatives and friends, but other than getting a little moral support, that may not prove too helpful. You can always consult a professional person such as a lawyer or an accountant. Either of these can be a good move, but may not be enough. An accountant generally deals in financial situations that have not yet gone off the rails, so to speak. He can recognize the negative reality of your situation, but may not know enough of the details of the options available to design a specific plan to get you out of trouble. Of course that depends on how bad the situation has become.
A lawyer is usually there to give a different kind of advice. In fact, unless you consult a lawyer specializing in insolvency matters there will likely be a practical limit to what a solicitor can do to help, again depending on how far things have deteriorated.
A financial consultant is likely to be a bit like an accountant in that he’s used to dealing with solvent situations and will not have a fluency with the practical and administrative details of the options available to you if your situation has become insolvent.
So we come back to the Licensed Insolvency Trustee as the only truly qualified Bankruptcy Counselor Toronto, or any other place.
If you need advice about what to do now that you have, or are about to fall behind with your credit card and other debt payments and want to retain some kind of control over your situation, the Licensed Insolvency Trustee is the go to guy. As a Bankruptcy Counselor Toronto, or elsewhere, the Trustee will not be your advocate like a lawyer would, but at Richard Killen & associates Ltd. we provide financial debt counselling services where in we will analyze your situation and explain it to you in understandable terms so that you can know what will be the best option for you to take to resolve the problem in a dignified and responsible manner. Is there a better way to take care of a problem?
Contact Richard Killen
FREE No Commitment Consultation
Contact us now for a fresh start!
“Serving Toronto & the GTA for over 25 years.”
Recent Blog Posts
- Why More Canadians Are Choosing Consumer Proposals for Debt Relief and Financial Recovery
- Consumer Proposal vs. Bankruptcy in Ontario: How Income and Assets Decide Your Best Route
- Are You Managing Debt or Just Surviving It? 10 Warning Signs It’s Time to Seek Debt Relief Solutions in the GTA
- Borrowing for Home Renovations in the GTA: Questions to Ask Before Taking on More Debt and How an LIT Can Help
- Back-to-School Expenses Are Adding Up: How to Prepare Without Going Into Debt Help Ontario