

Back-to-School Expenses Are Adding Up: How to Prepare Without Going Into Debt Help Ontario
As families across the GTA gear up for the new school year, the reality is clear: back-to-school costs are climbing, and many households are turning to credit cards to cover the gap. The growing need for debt help Ontario highlights how quickly seasonal expenses can strain budgets, especially when existing obligations already feel overwhelming.
Why Back-to-School Costs Hit Hard
Every September, families across the GTA face a surge of expenses that go far beyond pencils and notebooks. The back-to-school season has become one of the most financially demanding times of the year, especially for households already balancing monthly bills.
- School supplies Canada now include laptops, tablets, and specialized calculators — items that can cost hundreds of dollars.
- Rising cost of living Canada means essentials like groceries, rent, and transportation already stretch paycheques thin, leaving little room for seasonal extras.
- Clothing and footwear for growing children add another layer of expense, especially when schools require uniforms or specific gear.
- Extracurricular activities — sports, music lessons, or after-school programs — often require registration fees, equipment, and travel costs.
- Parents who rely on credit cards to cover these costs risk accumulating credit card debt Canada, which can quickly snowball if balances aren’t paid off.
For many families, these combined pressures make September feel like a second holiday season — but without the same planning or savings buffer.
Common Financial Mistakes Families Make
When faced with rising back-to-school costs, families often fall into predictable traps that worsen financial strain. Recognizing these mistakes early can help avoid long-term consequences.
- Impulse spending: Parents may feel pressured to buy brand-name backpacks, shoes, or electronics to keep up with peers, even when affordable alternatives exist.
- Last-minute shopping: Waiting until the week before school starts often means paying full price instead of taking advantage of summer sales or clearance events.
- Overlooking hidden costs: Transportation passes, extracurricular fees, and lunch programs can add hundreds of dollars to the budget but are often forgotten until the bills arrive.
- Ignoring repayment priorities: Families already carrying Canadian household debt sometimes delay payments to free up cash for school costs, which can damage credit scores and increase interest charges.
- Skipping financial planning: Without a clear budget, money disappears quickly on small purchases — snacks, subscriptions, or trendy accessories — leaving little for essentials.
- Neglecting financial literacy: Many parents don’t involve children in budgeting conversations, missing an opportunity to teach them about managing money during one of the most expense-heavy seasons.
These missteps often lead to mounting financial stress Canada, making it harder to enjoy the excitement of a new school year.
Smart Strategies to Prepare Without Going Into Debt
Back-to-school season doesn’t have to drain your wallet or push you further into borrowing. With the right planning and creative approaches, families across the GTA can ease the financial stress while still giving kids what they need to succeed.
1. Build a Seasonal Budget Early
Start planning in July or August to spread costs over several paycheques.
- Separate essentials (uniforms, school supplies Canada) from extras (designer clothes, accessories).
- Factor in hidden costs like bus passes, extracurricular fees, and lunch programs.
- Use digital budgeting apps to track spending and avoid surprises.
2. Shop Smart and Take Advantage of Deals
Retailers often run promotions leading up to September.
- Compare prices online before heading to stores.
- Buy in bulk for items like notebooks and pens.
- Look for gently used electronics or clothing through community swaps or online marketplaces.
3. Tap Into Community Support
Families don’t have to shoulder costs alone.
- Community programs Toronto often provide free or discounted supplies.
- Local charities and school boards sometimes run backpack drives or clothing exchanges.
- Swap events with neighbors can cut down on clothing and accessory expenses.
4. Teach Kids Financial Awareness
Involving children in the process helps them understand the value of money.
- Set spending limits together for clothing or accessories.
- Encourage them to prioritize needs over wants.
- Use back-to-school shopping as a chance to teach budgeting basics.
5. Reduce Stress With Creative Alternatives
Financial strain often leads to emotional stress, but small adjustments can make a big difference.
- Plan family “shopping days” with a set budget to avoid impulse buys.
- Spread out purchases — buy essentials first, then add extras later in the semester.
- Explore loyalty programs or cashback apps to stretch every dollar.
6. Reuse and Refresh What You Already Have
Instead of buying everything new, look at what can be carried over from last year.
- Backpacks, lunch bags, and binders often last more than one school year.
- Repurpose household items (storage bins, containers) for organizing school materials.
- Add a personal touch — stickers, patches, or DIY designs — to make reused items feel fresh and exciting for kids.
By combining reuse strategies with smart planning, families can stretch their dollars further and reduce the stress of September shopping. One of the most effective ways to stay on track is to map out expected costs in advance — which is where a clear budget framework becomes invaluable.
Back-to-School Sample Budget Template
Back-to-school season often feels like a financial juggling act, with families trying to balance everyday expenses alongside the sudden surge of school-related costs. Creating a clear budget not only helps track where money is going, but also ensures essentials are covered first while leaving room for extras without relying on credit. Here’s a simple framework families can adapt to their own situation:
- School Supplies (notebooks, pens, calculators, tech): $150–$300
- Clothing/Uniforms (shoes, jackets, gym wear): $200–$400
- Extracurricular Activities (sports, music, clubs): $100–$250
- Transportation (bus passes, gas, parking): $75–$150
- Lunch & Snacks (monthly meal prep or school programs): $100–$200
- Miscellaneous (field trips, subscriptions, accessories): $50–$100
Tip: Adjust these categories based on your child’s age and school requirements. Track actual spending against your budget to avoid surprises.
When Existing Debt Makes Back-to-School Tough
For many families across the GTA, September isn’t just about new beginnings — it’s also about new bills. When household budgets are already stretched thin, the added costs of school supplies Canada, clothing, and extracurricular activities can feel overwhelming. Parents often find themselves choosing between covering back-to-school expenses or keeping up with existing obligations like rent, utilities, or credit card payments.
This financial juggling act can quickly lead to:
- Credit card debt Canada piling up as families rely on high-interest borrowing to cover essentials.
- Missed payments on existing loans or bills, which can damage credit scores and increase stress.
- Heightened financial stress Canada, making what should be an exciting season feel like a burden.
For households already carrying significant Canadian household debt, back-to-school season can be the tipping point. That’s why professional guidance becomes essential — not just to manage September’s costs, but to create a sustainable plan for the months ahead.
How a Consumer Proposal Works
One of the most effective solutions available through a Licensed Insolvency Trustee is a formal repayment arrangement with creditors. This option is designed for families who want to avoid bankruptcy but need relief from mounting unsecured debt.
Here’s how it helps:
- Consolidates multiple obligations into one predictable monthly payment.
- Reduces the overall balance owed, giving families breathing room.
- Stops collection calls, wage garnishments, and legal actions.
- Protects assets like your home or car while restoring financial stability.
For parents facing September costs, this type of structured plan can make a huge difference. Instead of worrying about how to pay for supplies while juggling overdue bills, families can focus on essentials knowing their obligations are being managed in a legally binding way.
Take Control This Back-to-School Season
Back-to-school season doesn’t have to mean financial strain. With careful planning, smart shopping, and professional guidance, families can prepare without falling deeper into debt. And if existing obligations already make September overwhelming, remember that a Licensed Insolvency Trustee can provide trusted solutions.
Our firm operates across Toronto, Mississauga, Brampton, and the GTA, offering personalized support for families under pressure. Whether you’re facing credit card debt Canada, considering a consumer proposal Ontario, or exploring bankruptcy alternatives, our team is here to guide you.
Call us today at 1-888-545-5365 for a free consultation or book online to schedule your free consultation at the office most convenient for you. Taking this step now can help you regain control and move forward with confidence.
How to Tell If Your Summer Debt Requires a Consumer Proposal GTA or Just a Better Budget
For many across the Greater Toronto Area, summer is the season to finally breathe, travel, and make memories. But between patio season in downtown Toronto, cottage trips up north, kids’ day camps, and back-to-school shopping, the financial costs add up quickly.
By September, when credit card statements arrive, a familiar wave of anxiety sets in.
If you are staring at your bills feeling overwhelmed and wondering how to manage summer debt, you aren’t alone. For many residents across Ontario, those end-of-summer bills reveal a much larger issue. You might be asking yourself: Did I just overspend a bit this season, or am I in real financial trouble?
Here is a look at how summer spending can push an already tight budget over the edge, the key signs you need a consumer proposal, and how to take back control of your financial future.
The Iceberg Effect: Why Summer Debt Hits So Hard in the GTA
In a high-cost region like the Greater Toronto Area—where mortgages, rent, groceries, and transit absorb the vast majority of household take-home pay—most budgets operate with almost zero breathing room.
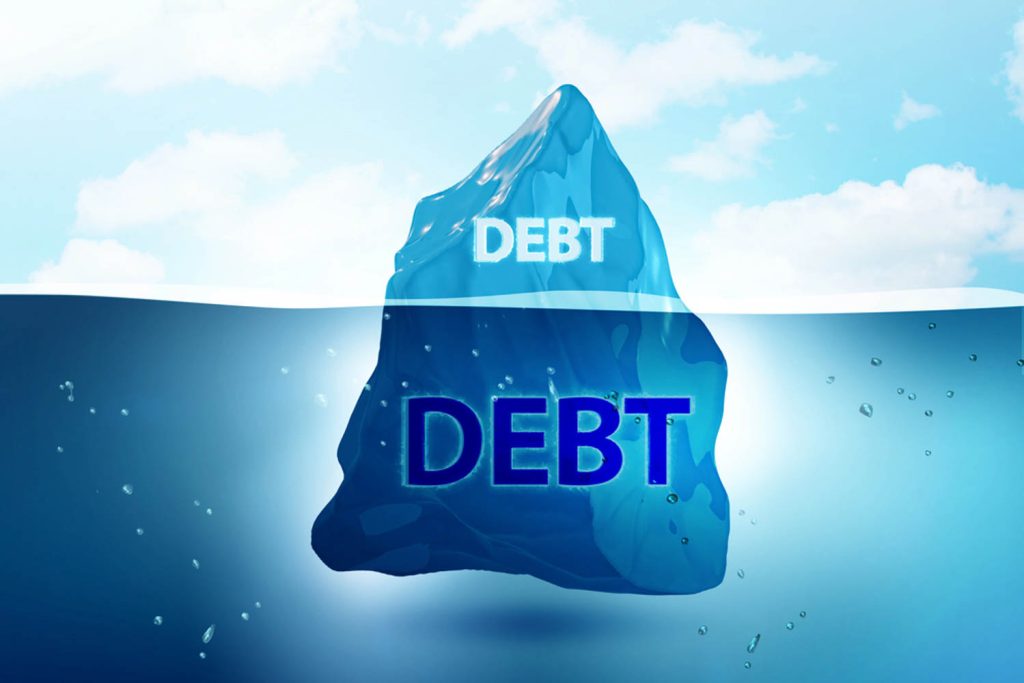
When September hits, many people assume that a $2,000 or $3,000 summer balance is the sole problem. But that seasonal balance is rarely the root cause of financial distress—it’s just the tip of the iceberg.
WHAT YOU SEE (The Tip)
[ $2,500 Summer Credit Card Bill ]
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~ (Waterline)
WHAT IS UNDERNEATH (The Iceberg)
$18,000 existing high-interest card/LOC balances
21.99% compounding interest rates
$500+/mo spent just paying interest (not principal)
GTA cost-of-living eating up cash flow
How the Iceberg Effect Actually Plays Out:
- The Visible Tip (The Summer Surge): You put vacations, kids’ day camps, patio dinners, or weekend road trips on credit, planning to “pay it off in the fall.”
- The Hidden Mass (Pre-Existing Debt + GTA Cost of Living): Underneath that new summer balance sits existing debt—a line of credit from last year’s car repair, a lingering balance on a rewards card, or high monthly housing costs that prevented you from saving a cash safety net.
- The Current (Compounding Interest): Once that new summer debt lands on top of existing balances at 19.99% to 24.99% interest, the math breaks. A $2,500 summer addition doesn’t just add $2,500 to what you owe—it increases your monthly interest charges, eating up whatever cash flow you had left to pay down the principal.
A Quick Breakdown:
Imagine carrying $15,000 in credit card debt at 21% interest. Your minimum payment is roughly $400/month, but around $260 of that goes straight to interest.
When summer adds another $3,000 to that card, your minimum payment jumps, and now over $300 a month vanishes into interest alone. Suddenly, you aren’t paying down your summer vacation—you’re stuck on a treadmill paying bank interest while struggling to afford basic GTA living costs.
Summer spending didn’t break your budget on its own; it simply pushed a fragile financial foundation underwater.
The “Dam Break” Test: Self-Correction vs. Formal Debt Relief
How do you know if your post-summer debt is a temporary bump or a sign that you need formal intervention? Weighing debt consolidation vs. a consumer proposal starts with looking honestly at your situation:
Scenario A: A Temporary Leak (Self-Correction Is Possible)
You likely do not need a Consumer Proposal if:
- Your total debt increase is strictly limited to recent summer purchases (e.g., under $5,000).
- You can realistically pay off the balance within 6 to 12 months by cutting back on non-essentials.
- Your credit score remains strong, allowing you to qualify for a standard debt consolidation loan or a low-interest balance transfer credit card.
Scenario B: The Dam Has Broken (Consumer Proposal Territory)
It may be time to look into formal debt relief if:
- Summer spending was stacked on top of existing balances, bringing your total unsecured debt to $10,000 or more.
- You are only able to make minimum payments, meaning most of your money goes toward interest rather than reducing what you owe.
- You rely on credit cards or payday loans to cover basic living expenses because cash flow is tied up in debt payments.
- Thinking about upcoming autumn costs and the winter holiday season brings a feeling of dread.
How a Consumer Proposal Can Reset Your Finances
If you find yourself in Scenario B, trying to budget your way out without structural relief can lead to years of treadmill-like stress. A consumer proposal in the GTA is a legal debt settlement process governed by Canadian federal law that allows you to pay back a portion of what you owe based on what you can actually afford.
If high-interest debt is pulling you under, a proposal is often the most effective route for credit card debt relief in Ontario. Here is why:
- Debt Reduction: In most cases, a Consumer Proposal reduces total unsecured debt by 50% to 80%, wiping out the remaining balance upon completion.
- 0% Interest: Interest rates freeze immediately. Every dollar you pay goes directly toward settling your agreed proposal amount.
- One Fixed Monthly Payment: All eligible unsecured debts—credit cards, personal loans, lines of credit, and tax debt owed to the CRA—are consolidated into a single, manageable monthly payment for up to 5 years.
- Immediate Protection: Once filed, a legal “stay of proceedings” takes effect. This immediately stops creditor phone calls, wage garnishments, and legal threats.
- Asset Security: Unlike bankruptcy, you keep your assets, including your house, car, and savings accounts.
What to Consider: The Trade-Offs
A Consumer Proposal is a formal legal agreement, and it is important to understand the realities involved before proceeding:
- Credit Impact: Filing a proposal places an R7 rating on your credit report for 3 years after the proposal is fully paid off (or 6 years from the date of filing, whichever comes first).
- Strict Adherence: Missing three monthly payments without filing an amendment will cause the proposal to default, restoring the original debt and interest.
- Formal Process: It must be administered by a Licensed Insolvency Trustee in the GTA—the only professionals in Canada legally authorized to file and manage insolvency proceedings.
Your Step-by-Step Action Plan for Fall
If you are feeling overwhelmed by summer debt, taking action early in the autumn prevents compounding interest from spilling over into the holiday season.
- Calculate Your Total Unsecured Debt: Add up all balances across credit cards, lines of credit, store cards, and overdrafts.
- Run a 60-Day Cash Flow Test: Deduct your essential living costs (rent/mortgage, utilities, food, transit) from your monthly income. Is there enough left over to meaningfully reduce your principal balance within a reasonable timeframe?
- Speak with a Licensed Insolvency Trustee: Book a free, confidential consultation with an LIT. They will review your entire financial picture and explain all available options—including budgeting tools, credit counselling, consumer proposals, and bankruptcy—with no obligation to proceed.
Turn Your Summer Setback into a Fresh Start
A summer spending surge doesn’t mean you’ve failed financially—it is often simply the signal that your current debt load is no longer sustainable.
If you are ready to break the cycle of debt and regain peace of mind, contact our team of experienced Licensed Insolvency Trustees in the GTA today for a free, no-judgment consultation. Call us for a free consultation at 1-888-545-5365 or schedule an appointment with a LIT near you.
How the Cost of Living in Canada Is Reshaping Family Finances — and Paths to Debt Relief
For many Canadian families, financial stability is becoming harder to maintain. The challenge is no longer just managing occasional unexpected expenses—it is finding ways to keep up with the steady increase in the cost of everyday life.
The cost of living in Canada has changed the way many households plan, spend, and save. According to Statistics Canada, shelter and food remain two of the largest components of household spending, while inflation has contributed to higher prices across many essential categories. At the same time, Canadian household debt remains a significant concern, leaving many families with less financial flexibility when unexpected expenses arise.
For households already feeling stretched, even small increases in monthly expenses can create difficult choices: paying down debt, covering essential bills, or saving for the future. As financial pressure continues to build, more Canadians are looking for answers and exploring what options are available when traditional budgeting is no longer enough.
Why Canadian Families Are Feeling the Financial Pressure
The rising cost of living in Canada has affected nearly every aspect of daily life. Although inflation has moderated from its peak, many prices remain significantly higher than they were just a few years ago.
Today, many families are paying more for:
- Groceries
- Transportation
- Childcare
- Insurance
- Household essentials
As a result, there’s less room in household budgets for savings, emergencies, or unexpected expenses.
According to Statistics Canada, the Consumer Price Index (CPI) remains above pre-pandemic levels. While inflation has slowed, the overall cost of goods and services remains elevated. Many families are now spending substantially more each month for the same necessities, putting additional pressure on household budgets.
These financial pressures affect more than monthly expenses—they can also impact emotional well-being. Ongoing financial strain may contribute to:
- Stress and anxiety
- Disrupted sleep
- Relationship tension
- Difficulty planning for the future
The Financial Consumer Agency of Canada (FCAC) has found that financial stress is closely linked to lower financial well-being, particularly among households carrying higher levels of debt or struggling to meet monthly obligations.
When most of a household’s income goes toward essential expenses, it becomes increasingly difficult to:
- Build emergency savings
- Pay down debt
- Prepare for unexpected costs
- Reach long-term financial goals
While budgeting remains an important financial habit, there comes a point where rising expenses and growing debt make it difficult to regain control through budgeting alone. Recognizing when professional support may be needed can help families protect both their financial health and overall well-being.
Housing Costs Continue to Put Pressure on Families
Housing is typically the largest monthly expense for Canadian families, and affordability remains a significant concern.
Whether renting or owning a home, many Canadians continue to face:
- Higher mortgage payments
- Rising rental costs
- Increasing property taxes
- Higher maintenance and repair expenses
These pressures are especially noticeable across Ontario and the Greater Toronto Area, where housing costs consume a large portion of household income.
The Canada Mortgage and Housing Corporation (CMHC) has consistently reported that housing affordability remains one of Canada’s most pressing economic challenges, with higher financing costs reducing affordability for both homeowners and prospective buyers.
When a significant portion of income goes toward housing, there’s often little flexibility to absorb other rising expenses. Even relatively small unexpected costs can quickly disrupt a family’s financial stability—such as:
- Vehicle repairs
- Medical bills
- Home maintenance
- Emergency travel
Why More Canadians Are Relying on Credit
As incomes struggle to keep pace with expenses, many households have turned to borrowing to bridge the gap.
Using credit occasionally can be part of healthy financial management. However, relying on credit to pay for everyday necessities can create a cycle that’s increasingly difficult to break.
Common expenses being placed on credit include:
- Groceries
- Utilities
- Fuel
- Rent
- Other household bills
According to Statistics Canada, Canadian households owed approximately $1.77 in credit market debt for every dollar of disposable income in late 2025. This reflects the growing financial pressure many families face as they manage rising living costs.
Recent reports from Equifax Canada also show:
- Consumer debt balances remain elevated.
- Credit card usage continues to increase.
- Missed payments are becoming more common among some households.
Many Canadians are now carrying multiple forms of debt, including:
- Credit cards
- Lines of credit
- Personal loans
- Auto loans
- Mortgage debt
While borrowing may provide temporary relief, repayment becomes more challenging as interest charges accumulate.
When Credit Card Debt Becomes Unmanageable
Persistent credit card debt is often one of the earliest signs that financial challenges are becoming more serious.
According to TransUnion Canada, many Canadians continue to carry higher revolving credit balances than in previous years. Elevated interest rates have also made these balances significantly more expensive to repay.
As interest accumulates, minimum monthly payments may do little to reduce the overall debt.
You may benefit from seeking professional advice if you find yourself:
- Making only minimum monthly payments
- Using one credit card to pay another
- Borrowing to cover everyday living expenses
- Falling behind on bills
- Receiving collection calls
- Having little or no emergency savings
These situations don’t necessarily mean bankruptcy is your only option. In many cases, debt relief solutions can help you regain control before your financial situation becomes more severe.
How a Licensed Insolvency Trustee (LIT) Can Help
When budgeting and traditional repayment strategies are no longer enough, speaking with a Licensed Insolvency Trustee (LIT) can help you understand your available debt relief options.
A Licensed Insolvency Trustee will:
- Review your complete financial situation
- Explain all available debt relief options
- Help you understand the advantages and drawbacks of each solution
- Recommend an approach based on your specific circumstances
Rather than focusing only on how much debt you owe, an LIT considers:
- Income
- Assets
- Household expenses
- Family situation
- Long-term financial goals
This allows them to recommend a solution that is realistic and sustainable.
Consumer Proposals: A Debt Relief Option for Eligible Canadians
For many individuals struggling with unsecured debt, a consumer proposal may offer an alternative to bankruptcy.
A consumer proposal allows eligible Canadians to:
- Repay a portion of their unsecured debt
- Make affordable monthly payments
- Stop interest from accumulating on included debts
- End collection activity
- Prevent further legal action from participating creditors
The Bank of Canada has noted that households with higher debt levels and limited financial buffers are more vulnerable to unexpected expenses or income disruptions. Seeking professional advice early can help Canadians understand their options before financial challenges become more difficult to manage.
An LIT can determine whether a consumer proposal is appropriate for your circumstances, explain the process, and guide you through each step.
Seeking Debt Relief Before the Situation Gets Worse
Many Canadians delay seeking help because they hope their financial situation will improve on its own. However, waiting often allows debt to grow while interest charges continue to accumulate.
Today’s financial challenges include:
- Higher housing costs
- Persistent inflation
- Rising everyday expenses
- Increased reliance on credit
- Growing financial stress
While budgeting remains an important financial tool, there are times when reducing expenses and adjusting spending habits are no longer enough.
It may be time to explore professional debt relief options if you are:
- Struggling to keep up with payments
- Using credit to cover everyday necessities
- Feeling overwhelmed by debt
- Watching balances continue to grow
Speaking with a Licensed Insolvency Trustee (LIT) can provide clarity about your available solutions, including whether a consumer proposal or another debt relief option may be appropriate. An LIT can review your financial circumstances, explain your options, and help you make an informed decision without pressure.
Get Professional Debt Advice Today
If you’re feeling overwhelmed by debt, we’re here to help you understand your options and take the next step toward financial stability. As a Licensed Insolvency Trustee (LIT), we provide honest, professional guidance to help you find a solution that fits your unique situation.
With offices across the Greater Toronto Area, our team is available to meet with you at a location that’s convenient for you. Reach out today to speak with a local LIT and learn how we can help you move forward with confidence. Call 1-888-545-5365 for a free consultation or book an appointment at one of our convenient GTA offices.
Debt Repayment vs Vacation: How to Balance Fun and Financial Freedom
As a Licensed Insolvency Trustee, I often speak with Canadians trying to make sense of debt repayment vs vacation decisions as summer approaches.
Summer in Canada brings a familiar tension for many households: the desire to enjoy a well-earned vacation versus the responsibility of paying down credit obligations. Whether it’s a road trip to the Maritimes, a week at a cottage in Ontario, or simply trying to make the most of the warmer months, the pressure to spend can create challenges when trying to stay on track with managing debt in Canada.
As a Licensed Insolvency Trustee, I work with Canadians every day who are trying to find a realistic approach to balance debt and lifestyle. The good news is that you do not necessarily have to choose between enjoying your summer and working toward financial stability—but you do need a clear plan.
Understanding Summer Spending And Debt
Before we talk about balance, it’s important to understand how quickly summer spending and debt can become connected.
Vacations rarely stop at flights and hotels. There are meals, gas, activities, shopping, and unplanned expenses. Even a modest trip can impact your overall debt repayment plan, especially if it is funded with credit.
For individuals already carrying financial liabilities—credit cards, lines of credit, payday loans, or tax arrears—this extra spending can quietly delay financial recovery by months or even years.
The question is not whether you deserve a break. The real question is: can you afford the break without compromising your financial stability?
When I review client budgets, I often see how quickly debt repayment vs vacation decisions become blurred. What starts as a small getaway can turn into months of additional repayment stress.
Step 1: Start with a Clear Financial Snapshot
Understanding your numbers is the foundation of any debt repayment plan.
Before making summer plans, list:
- Monthly income
- Essential expenses
- Ongoing payments
- Discretionary spending
When clients begin managing debt in Canada, they often start to see how much flexibility they truly have in their debt repayment vs vacation decisions.
Many are surprised at this stage. They often discover that their “available” vacation budget is either smaller than expected—or non-existent without taking on more financial commitments.
A realistic financial snapshot helps you understand how to balance debt and lifestyle without relying on credit.
Step 2: Set a “No-New-Debt” Vacation Rule
One of the most important principles I share as a Licensed Insolvency Trustee is simple: do not fund summer spending and debt at the same time.
If a vacation requires borrowing, it becomes part of your debt repayment plan, not a break from financial pressure.
Instead, build a small savings buffer—even if it’s modest. This approach supports better managing debt in Canada while still allowing some enjoyment.
Step 3: Redefine What a “Vacation” Means
One of the biggest financial mindset shifts I recommend as an LIT is this: vacation does not have to mean expensive travel.
A key part of how to balance vacation spending while paying off debt in Canada is setting expectations early, before any plans are made.
A balanced approach might include:
- Shorter trips instead of long vacations
- Lower-cost local travel
- Prioritizing essential ongoing payments first
- Planning vacations only within available savings
This is where debt repayment vs vacation becomes a matter of intentional planning rather than impulse spending.
Step 4: Use a Priority-Based Budget Approach
If you decide to travel, the key is prioritization. Your budget should reflect this order:
- Housing and utilities
- Food and transportation
- Minimum repayment obligations
- Savings for emergencies
- Vacation spending (only if funds remain)
If vacation sits above repayment obligations or essentials, financial instability is likely to follow.
A responsible summer budget might include setting aside a fixed amount each pay period—even $25 to $100—specifically for leisure. The key is consistency and limits.
When clients are actively working on a debt repayment vs vacation strategy, this type of structure is what helps prevent short-term spending from disrupting long-term progress.
Finding the Right Balance
Here’s how I explain it to clients trying to balance debt and lifestyle in real life: You do not need to choose between financial responsibility and enjoying life. But you do need to make decisions that reflect your current financial situation—not your ideal one.
To put this into perspective, consider how different choices can play out over just one summer:
Scenario A: No plan
You book a $4,000 family vacation on credit, paying only the minimum afterward. Interest builds, and your debt repayment plan falls behind. By fall, stress increases and financial pressure grows.
Scenario B: Balanced plan
You set aside $1,500 for travel, maintain your debt repayment plan, and choose low-cost activities. By fall, your summer spending and debt remain controlled, and your financial position improves.
The difference isn’t about deprivation—it’s about intentional choices.
A balanced approach in real life often looks like:
- A scaled-back vacation instead of a costly one
- A planned savings-based trip instead of credit-funded travel
- Prioritizing reduction of financial obligations first, then increasing travel later
- Seeking professional help when financial obligations are no longer manageable
Financial freedom does not come from avoiding enjoyment altogether—it comes from making decisions today that support both your present and your future.
When Debt Becomes More Than a Budget Problem
For some Canadians, managing debt in Canada is no longer just about budgeting or cutting back—it becomes a barrier to everyday life.
If you are struggling to meet basic expenses, or if your debt repayment plan no longer feels manageable, summer spending may not be your primary concern.
If you are experiencing any of the following, it may be time to reassess:
- Only making minimum payments
- Using credit for daily expenses
- Falling behind on bills
- Collection activity
- Ongoing financial stress
- No clear path to reducing debt
At this stage, the issue is no longer just debt repayment vs vacation—it is about finding a sustainable solution.
How a Licensed Insolvency Trustee Can Help
This is where a Licensed Insolvency Trustee becomes an important resource—not just during a financial crisis, but also when planning for recovery.
An LIT is the only professional in Canada authorized to administer government-regulated debt solutions under the Bankruptcy and Insolvency Act. Our role is to provide options that are legal, structured, and designed to help Canadians regain financial stability.
Here are the two most common solutions we discuss:
1. Consumer Proposal
A Consumer Proposal allows you to negotiate with your creditors to reduce your total debt and consolidate it into one affordable monthly payment—often with no interest.
Benefits include:
- Reduced total debt balance
- Frozen interest
- One manageable monthly payment
- Protection from creditors and collection calls
This option allows many Canadians to keep their assets while regaining control of their finances.
2. Bankruptcy
Bankruptcy is a legal process designed for individuals who cannot realistically repay their debts. While it is often misunderstood, it exists to provide a fresh financial start.
It may:
- Eliminate most unsecured debts
- Stop wage garnishments and collection action
- Provide relief from overwhelming financial pressure
A trustee will always assess whether this is the appropriate option or whether alternatives, like a Consumer Proposal, are better suited.
Beyond the Summer: Building Lasting Financial Balance
As a Licensed Insolvency Trustee, my advice is simple: protect your future first.
Summer is meant to be enjoyed, but I have seen how summer spending and debt decisions can create long-term financial strain when they are not planned carefully. A vacation should not compromise your debt repayment plan or your ability to move forward financially.
That does not mean you need to avoid all spending. It means making informed decisions that support your ability to balance debt and lifestyle over the long term.
If debt is becoming difficult to manage, do not wait. Speaking with a Licensed Insolvency Trustee can help you understand your options, whether that involves a Consumer Proposal or bankruptcy, depending on your situation.
The goal is not just to get through the summer—it is to create financial stability that lasts beyond it. With the right plan in place, debt repayment vs vacation does not have to be a conflict you face every year.
If you’re struggling with debt, my advice is not to wait. Speak with a Licensed Insolvency Trustee in your area and book a confidential consultation to understand your options and take control of your financial future. Call us today at 1-888-545-5365
Job Loss & Debt in Canada: How a Licensed Insolvency Trustee Can Help You Regain Control
Losing your job is one of the most stressful financial events a person can experience. In Canada, where household debt levels are already high, even a short period of unemployment can quickly turn manageable obligations into overwhelming pressure. Mortgage payments, rent, credit cards, lines of credit, and car loans do not pause just because income does.
As a Licensed Insolvency Trustee, I often work with individuals experiencing job loss and debt who are unsure of their next steps. The good news is that debt relief in Canada is available through structured, legal options that can provide immediate protection and a clear path forward.
Let’s look at how a Licensed Insolvency Trustee can help after job loss in Canada, including how legal protections stop creditor actions, and how options like a Consumer Proposal can be used strategically—even while you are on Employment Insurance (EI).
The Financial Shock of Job Loss
Losing employment doesn’t just reduce your income—it disrupts your entire financial stability and can quickly lead to debt pressure. Here’s how it typically unfolds:
- Immediate income reduction: Even if you qualify for Employment Insurance (EI), the benefit is typically less than your regular paycheque.
- Debt obligations remain unchanged: Credit card bills, loan payments, and mortgage obligations don’t pause just because your income does.
- Collection pressure increases: Missed payments can trigger collection calls, wage garnishments, or even lawsuits.
- Stress compounds quickly: Instead of focusing on finding new work, much of your energy is spent worrying about creditors.
Even with EI benefits, there is often a significant gap between what you receive and what you were earning. That gap is where financial stress can escalate into serious debt challenges.
The emotional impact is just as important. Job loss creates urgency, but financial pressure can make it harder to focus on rebuilding your career. This is where a Licensed Insolvency Trustee can provide structured relief and help create stability during a difficult transition.
How a Licensed Insolvency Trustee Provides Breathing Room
When you’re facing job loss and mounting debt, the most immediate relief an LIT provides is breathing room. By filing a Consumer Proposal or Bankruptcy, we trigger an automatic stay of proceedings—a legal protection that stops collection calls, wage garnishments, and lawsuits in their tracks. This protection gives you the space to focus on what matters most: rebuilding your career and stabilizing your income.
But our role goes beyond simply halting creditor pressure. A Licensed Insolvency Trustee is the only professional in Canada legally authorized to administer insolvency processes under the Bankruptcy and Insolvency Act. That means we’re not debt collectors—we’re neutral officers of the court. Our job is to help you and your creditors reach a fair, legally binding resolution that works for both sides.
In practice, this means we provide:
- Immediate legal protection so you can redirect your energy toward a career transition.
- Structured debt solutions like Consumer Proposals, tailored to your current income—even if you’re on EI.
- Clear guidance through complex financial decisions, ensuring you understand your rights and options.
- Neutral oversight that balances creditor expectations with your need for a fresh start.
The real value of an LIT during job loss is this: we give you control back. Instead of being consumed by creditor pressure, you gain a clear path forward, supported by a federally regulated professional whose sole purpose is to help Canadians overcome financial challenges.
Why This Matters During Career Transition
When you are between jobs, your most valuable resource is focus. Debt stress can quickly take that focus away from rebuilding your income and moving forward in your career.
By stabilizing your financial situation and legally addressing creditor pressure, you regain the ability to:
- Focus on job searching or retraining
- Make decisions without constant creditor pressure
- Avoid falling further behind financially
- Stabilize your day-to-day living situation
This is what I mean by creating breathing room—it is not only financial, but also practical and psychological. When the pressure from collection activity is reduced or removed, you are no longer reacting to your financial situation—you can start planning your next steps with clarity.
As a Licensed Insolvency Trustee, one of the most immediate changes I see is this shift: once creditor pressure is addressed through the appropriate legal process, clients are able to redirect their energy toward rebuilding stability instead of managing constant stress.
Common Misconceptions About Debt Relief During Job Loss
In my experience working with Canadians facing job loss, there are several misconceptions that often prevent people from getting help early. Addressing them directly can make a significant difference in your options and outcomes.
“I need a full-time job before I can restructure debt.”
Not true. You can file a Consumer Proposal even while receiving Employment Insurance (EI). Payments are structured around your current income, so you don’t have to wait until you’re back at work to take action. Acting early prevents debt from snowballing during unemployment.
“Bankruptcy is the only option if I lose my job.”
Many people assume job loss automatically means bankruptcy. In reality, a Consumer Proposal is often a better fit, especially if you want to keep your home, car, or other assets. Bankruptcy is just one tool—an LIT will help you explore all available options.
“Creditors won’t agree to reduced payments.”
Creditors frequently accept Consumer Proposals because they provide certainty. They know they’ll receive a portion of what’s owed, rather than risk non-payment. It’s a win-win: you regain control, and they secure repayment.
“Debt relief will ruin my credit forever.”
While a Consumer Proposal or Bankruptcy does affect your credit rating, it’s temporary. More importantly, it gives you a chance to rebuild. Many clients find that stabilizing debt and making consistent payments improves their financial profile faster than struggling with missed payments and collections.
“Talking to an LIT means I’ve failed.”
Seeking help is a proactive step, not a failure. Licensed Insolvency Trustees are federally regulated professionals whose role is to guide Canadians through financial challenges. Reaching out shows strength and determination to protect your future.
“Collection calls and wage garnishments can’t be stopped.”
They can. Once you file with an LIT, an automatic stay of proceedings legally halts collection activity. That means no more harassing calls, no more garnishments, and no more lawsuits related to debt. This protection is immediate and powerful.
Once these misconceptions are cleared up, it becomes easier to understand how solutions like a Consumer Proposal can provide real, structured relief during job loss.
Consumer Proposal Canada: A Proactive Solution While on EI
Many Canadians assume debt restructuring is only possible once they’re back to full employment. That’s not true. Even while receiving Employment Insurance (EI), you can file a Consumer Proposal Canada which is a legally binding agreement with your creditors to repay a portion of your unsecured debt over time, typically up to five years, and without interest.
A Consumer Proposal is often the most effective tool during periods of job loss or income disruption because it adapts to your financial reality. Payments are based on what you can afford today, not what you earned before. That flexibility means you can move forward even while on EI, in transition between jobs, or working reduced hours.
Here’s why a Consumer Proposal can be a smart move during job loss:
- Payments match your current income: Structured around EI or reduced wages, so they remain manageable.
- You keep your assets: Unlike bankruptcy, you don’t risk losing your home, car, or other essentials.
- Debt is reduced: Creditors often accept less than the full amount owed, preferring certainty over risk.
- Fixed monthly payments: Provides predictability and stability during uncertain times.
By filing a Consumer Proposal while unemployed, you prevent a temporary job loss from spiraling into a permanent financial crisis. Instead of falling further behind, you gain control, protect your assets, and create a clear path toward recovery.
Bankruptcy vs. Consumer Proposal: Choosing the Right Path
While Consumer Proposals are often preferred for those with some income or EI benefits, bankruptcy may also be appropriate in certain situations.
Bankruptcy is a legal process that eliminates most unsecured debts and provides a faster financial reset. It is not a failure—it is a structured solution designed for situations where repayment is not feasible.
An LIT will assess your situation carefully and explain both options transparently, including:
- Your income (including EI)
- Your assets
- Your total debt load
- Your future earning potential
The goal is not to push a solution, but to match the right tool to your circumstances.
Regaining Control and Rebuilding After Job Loss
Job loss is often a turning point. Many Canadians use this time to retrain, explore new paths, or consider opportunities they hadn’t previously thought about. But meaningful career transition requires focus—and financial stress can quickly take that focus away.
Debt relief is not just about stopping collection calls. It is about creating the stability needed to move forward.
By working with a Licensed Insolvency Trustee, you can gain structure and protection that helps you:
- Focus on job search or retraining without constant financial pressure
- Stabilize essential living expenses during your transition
- Rebuild confidence knowing there is a clear plan in place
- Begin improving your credit over time through structured repayment options where applicable
It is important to understand that insolvency solutions are not a reflection of failure. They are legal, structured tools designed to provide relief and a fresh start. Once immediate pressure is reduced, many people are able to re-enter the workforce sooner and rebuild with greater stability and confidence.
At its core, debt relief is about creating the financial and emotional space to move forward instead of being held back by past obligations.
Don’t Wait for Debt to Escalate: Let’s Take the First Step Together
If you are dealing with job loss and debt, I want you to hear this clearly: you are not out of options, but timing matters.
In my experience as a Licensed Insolvency Trustee, Canadians often wait too long, hoping things will improve once EI starts or employment resumes. Unfortunately, during that time, debt often continues to grow through interest, missed payments, and debt collection calls.
Speaking with a Licensed Insolvency Trustee does not mean you are filing for bankruptcy. It simply means you are understanding your options—including whether we can stop wage garnishment in Canada, reduce payments through a Consumer Proposal, or create a structured plan.
You do not have to navigate this alone.
Call us for a FREE consultation at 1-888-545-5365 or book a confidential consultation today. That first step is often where uncertainty turns into clarity—and where you begin moving from financial stress toward stability.
Summer Vacation on Credit? What a Licensed Insolvency Trustee Wants You to Know About Vacation Debt in Canada
For many Canadians, summer is something to look forward to all year. It’s a time to unwind, reconnect with family, and take a well-deserved break from routine—but for some, vacation debt in Canada is becoming an increasingly common part of the experience. As travel costs continue to rise, more people are turning to credit cards, lines of credit, or buy-now-pay-later options to fund their vacations.
As a Licensed Insolvency Trustee Canada professionals rely on, I understand the appeal. After a long winter or a stressful year, a getaway can feel essential. However, taking a vacation on credit can have longer-term financial consequences that aren’t always obvious at the moment. Before you book that flight or resort, it’s worth taking a closer look at the risks—and understanding when debt may signal a deeper problem.
The Hidden Cost of “Pay Later” and Credit Card Debt Canada
When you charge a vacation to a credit card, you’re not just paying for flights, hotels, or excursions—you’re also agreeing to pay interest on those purchases if the balance isn’t paid off in full right away.
In Canada, the average credit card interest rate hovers around 19% to 29%. That means a $5,000 vacation could end up costing significantly more over time if you carry a balance. For example, if you only make minimum payments, it could take years to pay off that trip—and you may end up paying thousands of dollars in interest alone. This is how credit card debt Canada households carry can quietly grow.
What starts as a one-time indulgence can quietly turn into long-term debt.
Why Travel Debt Can Spiral
Unlike essential expenses—such as housing, groceries, or transportation—a vacation is a discretionary purchase. That’s important, because when debt begins to pile up, discretionary spending is often the first place where financial strain becomes visible.
Here are a few ways travel debt can escalate:
- Layering debt: If your vacation is financed on a credit card that already carries a balance, you’re increasing your overall debt load and compounding interest.
- Underestimating costs: Travel budgets often expand beyond initial expectations. Meals, activities, tips, and unexpected expenses can add up quickly.
- Delayed repayment: After returning home, it’s easy to fall back into regular spending habits without aggressively paying down the vacation balance.
- Using credit to recover: Some individuals rely on additional credit—such as lines of credit or cash advances—to manage the original debt, creating a cycle that becomes difficult to break.
When Interest Outlasts the Memories
A vacation may last one or two weeks, but the financial impact can linger for months or even years. This is one of the most common patterns I see in my work as an LIT: short-term spending decisions leading to long-term financial stress.
It’s not unusual for individuals to come in for a consultation and realize that a portion of their current debt originated from past travel. While that doesn’t mean vacations are inherently problematic, it does highlight how easily debt can accumulate when repayment isn’t immediate or structured.
Is It a Bad Idea to Go Into Debt for a Vacation
If you’re considering financing a vacation, this is one of the most important questions to ask. In many cases, the answer depends on your ability to repay what you borrow quickly and without relying on additional credit. When repayment stretches over months or years, the cost of borrowing can outweigh the benefit of the trip itself.
When Travel Debt Becomes a Warning Sign
Debt, on its own, isn’t always a problem. Many Canadians use credit responsibly and pay it off regularly. However, there are signs that debt may be becoming unmanageable:
- You’re only making minimum payments on your credit cards
- Your balances continue to grow despite regular payments
- You’re using credit to cover everyday expenses like groceries or rent
- You feel stressed or anxious about your financial situation
- Collection calls or overdue notices are becoming more frequent
If a vacation on credit contributes to—or worsens—any of these issues, it may be time to take a closer look at your overall financial picture.
Questions to Ask Before You Book and How to Avoid Debt
If you’re considering financing a vacation with credit, take a moment to assess your financial situation honestly. Understanding how to avoid debt starts with asking the right questions:
- Can I afford to pay off this trip within a few months?
- Am I already carrying a balance on my credit cards?
- Do I have an emergency fund in place?
- Will this purchase affect my ability to cover essential expenses?
If the answer to any of these raises concern, it may be worth reconsidering your plans—or adjusting them to fit your current financial reality.
Practical Alternatives to Credit-Funded Vacations
Vacations don’t have to mean debt. With a little creativity and planning, you can enjoy summer without relying on high-interest cards. Here are some practical alternatives:
How to Avoid Vacation Debt
- Staycations with a Twist: Explore local attractions in Toronto, Brampton, or Mississauga without airfare costs. Think of it as being a tourist in your own city—visit museums, parks, or festivals you’ve never tried before. For example, spending a weekend at Toronto’s Harbourfront Centre during the Summer Music Festival or enjoying the Canadian National Exhibition (CNE) in August can feel just as exciting as a trip away. Even a couple of day trips can provide the refresh you’re looking for.
- Budget-Friendly Travel Options: Instead of international flights, consider road trips to nearby provinces or train travel within Canada. These options often cost less and still provide a sense of adventure. For example, many families choose a summer road trip to Algonquin Provincial Park in Ontario, which offers hiking, canoeing, and camping at a fraction of the cost of flying abroad. Booking off-season or mid-week can also save significantly.
- Shared Costs with Family or Friends: Travelling in groups allows you to split accommodation, transportation, and even food expenses. Renting a cottage together or sharing a road trip can make vacations more affordable and fun.
- Alternative Accommodations: Instead of hotels, consider camping, hostels, or short-term rentals. These options often provide unique experiences at a fraction of the cost.
- Micro-Adventures: Vacations don’t have to be long or far. A two-day camping trip, a visit to Banff National Park in Alberta, or even a summer afternoon at Wasaga Beach in Ontario can provide the same sense of escape without the financial burden. On the East Coast, Canadians often head to Cavendish Beach in Prince Edward Island, known for its stunning shoreline and family-friendly atmosphere. These nearby destinations are affordable, accessible, and offer the kind of refreshing break that doesn’t leave you with lingering debt.
- Experience Over Expense: Focus on activities that create memories rather than costly luxuries. Picnics, hikes, and community events often deliver more joy than expensive resorts.
Choosing one of these alternatives not only saves money but also ensures your vacation memories aren’t overshadowed by financial stress. With a little planning, you can enjoy summer adventures that feel rewarding both in the moment and long after you return home.
How a Licensed Insolvency Trustee can Help with Debt Relief Options Canada
As Licensed Insolvency Trustee Canada professionals, we are federally regulated experts who help Canadians deal with debt. If travel-related debt has become part of a larger financial challenge, you don’t have to navigate it alone.
An LIT can:
- Review your full financial situation in a confidential, judgment-free setting
- Explain all available options, including budgeting strategies, debt consolidation, debt relief options Canada residents can access, consumer proposals, and bankruptcy
- Help you understand the pros and cons of each approach
- Work with creditors to create a manageable repayment plan if appropriate
One of the most common solutions we help clients explore is a consumer proposal Canada residents often use. This is a legally binding agreement that allows you to repay a portion of your debt over time, often without interest, while protecting you from collection actions.
For individuals whose debt has reached a more severe level, bankruptcy may also be an option. While it’s not the right choice for everyone, it can provide a fresh financial start when other solutions are no longer viable.
Understanding your options is often the first step toward regaining control.
Take the First Step Toward Financial Relief
As a Licensed Insolvency Trustee, I often remind clients that avoiding debt isn’t about restriction—it’s about planning. If a traditional vacation doesn’t fit your budget right now, there are still plenty of ways to enjoy the summer without relying on credit.
If you’re already feeling the impact of travel-related debt, or if your overall financial situation is becoming difficult to manage, you don’t have to figure it out on your own. Speaking with a Licensed Insolvency Trustee can help you understand your options and take back control of your finances.
Whether you’re exploring debt relief options Canada residents trust or simply want clarity on your next steps, a confidential consultation can provide the guidance you need.
If vacation debt in Canada is starting to affect your ability to cover everyday expenses, now is the time to act. Reach out today to schedule a no‑obligation consultation and take the first step toward a more stable financial future. Call us for a FREE Consultation at 1-888-545-5365 or book a confidential appointment with a Licensed Insolvency Trustee to explore your options and protect your household budget.
The Canada Groceries and Essentials Benefit 2026: What It Means for Your Budget and Debt
Many Canadians are hearing about a new federal benefit launching in July 2026 designed to help with everyday costs like groceries and essentials.
At first glance, the Canada Groceries and Essentials Benefit 2026 sounds like welcome relief in a period of rising living expenses.
But for many households, the real question is not just what the benefit is—it’s how much of it you will actually receive, and whether anything affects it before it reaches your account.
As with most government support programs, the details matter more than the headline.
What Is the Canada Grocery Benefit 2026?
Formally known as the Canada Groceries and Essentials Benefit 2026, the CGEB is a proposed federal income-support program designed to help eligible Canadians manage the rising cost of basic household needs such as food and everyday essentials.
It is intended to replace or restructure existing GST/HST-related credits over time.
Eligibility and program structure are based on federal income guidelines and tax filing information. More details are outlined at the Government of Canada website – https://www.canada.ca
Canada Grocery Benefit Payment Dates 2026
The benefit is expected to be issued on a quarterly basis, based on income reported through your tax return.
In general terms:
- Payments are distributed throughout the year
- Eligibility is reviewed annually through tax filings
- Amounts vary depending on income and household size
Payment structures and eligibility rules are determined by federal guidelines published by the Government of Canada.
Canada Grocery Benefit 2026: Transition Fact Check
With the Canada Groceries and Essentials Benefit (CGEB) replacing the GST/HST credit system in 2026, there is growing confusion about how payments will work. Here are the key points to understand for your household planning:
Key transition points:
- A one-time transitional adjustment is expected during the switch from the GST/HST credit system in 2026
- The first quarterly CGEB payments are expected to begin in July 2026
- Eligibility will continue to be based on income and household composition
How the benefit is calculated:
- Payment amounts are based on income reported through your tax return
- The structure is designed to reflect rising costs of essential goods
- Payments are expected to be issued quarterly
Important CRA Consideration: Will I Get the Grocery Benefit If I Owe CRA?
If you owe money to the Canada Revenue Agency, some or all of your benefit may be applied directly toward outstanding balances through the CRA set-off program.
These rules are administered under Canada Revenue Agency guidelines available at their website https://www.canada.ca.
In these cases, the benefit may be reduced or redirected before it reaches your bank account.
Will You Actually See the Money
This is the question many households need to ask. If you owe CRA, your benefit may be partially reduced or even fully redirected to cover tax arrears or overdue balances. In some cases, the payment never reaches your bank account at all. Understanding this risk is critical for budgeting, because planning around money you may not receive can create unexpected shortfalls.
Debt-First Perspective: Where Households Feel the Pinch
Eligibility and payment dates are only part of the story. The real-world impact often hinges on debt. If you owe CRA, your benefit may never reach you directly. Instead, it can be redirected to cover tax arrears, overdue balances, or other obligations.
For households already stretched thin, this creates a budget shock factor. Families planning around quarterly payments may suddenly face shortfalls, forcing them to rely on credit cards or short-term loans to fill the gap. Even a $300 quarterly benefit applied to CRA debt instead of groceries can push a household toward borrowing at high interest rates—magnifying financial strain rather than easing it.
This makes the CGEB less of a guaranteed relief program and more of a debt-sensitive transfer. Relief only arrives if households are already clear of CRA obligations, which is why understanding the set-off rules is critical for financial planning.
The Impact on Household Budgets in 2026
On paper, the Canada Grocery Benefit 2026 is meant to help with everyday costs.
In practice, many households will still be managing:
- rising grocery prices
- fixed housing costs
- credit card or loan payments
- ongoing cost-of-living pressures
As a result, the benefit may provide temporary relief but is unlikely to fully offset broader financial strain.
Forward-Looking Insight: The Bigger Affordability Strategy
The CGEB is not a standalone measure—it’s part of Canada’s broader affordability framework. To understand its role, it helps to look at the bigger picture:
- Housing: Federal housing affordability measures, such as rent supplements or first-time buyer supports, often swallow any gains from grocery relief. Rising rents remain one of the largest pressures on household budgets.
- Childcare: The national childcare strategy aims to reduce monthly costs for families. When combined with grocery relief, this could free up hundreds of dollars—but only if both programs are accessible.
- Tax Credits: The CGEB is designed to replace or restructure GST/HST credits, signaling a shift toward more targeted affordability support. Alongside the Canada Child Benefit and Climate Action Incentive, it reflects Ottawa’s move to streamline benefits.
Taken together, these programs show a policy direction: targeted affordability supports rather than broad tax cuts. For households, this means relief will come in multiple forms, but none are silver bullets. Planning across housing, childcare, and debt management remains essential.
Why This Matters If You Have Debt
When household budgets are already tight, even small financial changes matter. If a portion of your benefit is redirected to CRA:
- expected income may be lower than planned
- monthly budgeting assumptions may need adjustment
- reliance on credit may increase to fill gaps
Over time, this can add pressure if other debts are already carrying interest. That’s why mapping your full affordability strategy before July 2026 is more important than relying on any single payment.
When a Temporary Benefit Isn’t Enough
Government benefits like the Canada Groceries and Essentials Benefit can provide short-term affordability relief, but they don’t resolve deeper financial challenges. For many households, the real issue isn’t just rising grocery costs—it’s the layered pressure of debt, housing, and childcare expenses that stretch budgets beyond capacity.
Even with quarterly payments, families may still be managing:
- credit card balances carrying high interest
- personal loans or lines of credit
- tax debt with CRA that reduces or redirects benefits
- fixed housing costs that rise faster than income
- childcare expenses that remain a major monthly burden
This is why the CGEB should be seen as one piece of a larger affordability puzzle. Relief from groceries helps, but it doesn’t eliminate the structural pressures of debt or the long-term costs of housing and childcare.
What Households Should Keep in Mind
The Canada Groceries and Essentials Benefit can provide meaningful support, but it’s important to see it in the context of your full financial picture. Key points to remember:
- Payments may be reduced or redirected if CRA balances are outstanding.
- Relief is temporary—housing, childcare, and debt costs remain ongoing.
- Quarterly payments can help with groceries but won’t erase existing financial pressures.
- Planning ahead matters more than relying on any single program.
By keeping these realities in mind, households can avoid budget shocks and make more informed decisions about how to manage both everyday expenses and long-term obligations.
If You’re Dealing With Debt or CRA Balances
For households carrying tax debt or other obligations, the CGEB may not provide the relief you expect. Benefits can be partially reduced or fully applied toward CRA arrears before reaching your account. That’s why proactive planning is essential.
A Licensed Insolvency Trustee (LIT) can help you:
- Review your total debt position, including CRA balances.
- Clarify how government benefits interact with outstanding obligations.
- Explore structured options such as Consumer Proposals to consolidate debt into manageable payments.
- Build a realistic plan to stabilize your finances before the benefit rollout.
Don’t wait until July 2026 to discover your benefit has been redirected. Call us today for a FREE Consultation 1-888-545-5365 or book a free, confidential consultation with a Licensed Insolvency Trustee to explore your options and protect your household budget while working toward financial freedom.
Is It Too Late to Fix Debt Before Tax Deadline?

If you’re feeling stressed about looming obligations and wondering whether it’s too late to fix debt before the tax deadline, you’re not alone. Many Canadians wait until the last minute to organize their finances, but there are still steps you can take to regain control and reduce financial stress. As a Licensed Insolvency Trustee serving Ontario, Toronto, and the GTA, I’ve guided countless individuals through situations like this, helping them explore options and take informed action.
Understanding the Deadline Pressure
Facing financial obligations at the end of the filing period can feel overwhelming. Unpaid balances, growing interest, or missed payments can trigger anxiety—but timing matters. Even in the final stretch, proactive steps can reduce penalties and make a meaningful difference.
Key points to keep in mind:
- Immediate action can limit interest and additional fees.
- Various programs exist to manage obligations before deadlines.
- Guidance from a trustee ensures you explore all tools available.
For Canadians seeking support, debt relief Canada programs and Ontario debt help services provide structured approaches to address these challenges effectively.
Common Misconceptions About Year-End Financial Obligations
Many people assume that once the deadline is near, nothing can be done. That’s not true. Understanding your options can prevent unnecessary panic:
- Some repayment arrangements can be initiated even days before the final filing date.
- Credit counselling isn’t just for insolvency; it can help prevent problems from escalating.
- Trustees can often negotiate on your behalf, reducing penalties or deferring interest.
Tax debt solutions exist to help individuals explore alternatives to immediate full repayment, providing flexibility and relief.
How to Deal with Debt and Pay Off Balances Before the Tax Deadline
Even as the filing deadline approaches, there are concrete steps you can take to regain control—and an insolvency professional can guide you every step of the way. With expert insight, you can prioritize obligations, explore repayment options, and develop a plan tailored to your circumstances.
Here’s how to approach it effectively:
- Review all financial statements:
List all outstanding balances, unpaid bills, and loans. Trustees can help identify overlooked obligations or opportunities to prioritize payments efficiently. - Prioritize urgent obligations:
Not all balances carry the same consequences. With their guidance, you can focus on high-priority payments first, minimizing interest charges and preventing escalation. - Explore repayment arrangements and professional solutions:
Insolvency professionals can provide insight into structured options that suit your situation, including:- Short-term loans or lines of credit: Can bridge immediate gaps when used responsibly.
- Payment deferral programs: Temporary postponements to ease cash flow without long-term impact.
- Structured repayment schedules: Spread balances over several months to reduce immediate pressure.
- Consumer proposals: Formal agreements to repay a portion of what you owe over time, often reducing total balances and halting collection actions.
- Debt consolidation programs: Combining multiple balances into a single monthly payment for easier management.
- Negotiated settlements with creditors: Trustees can approach creditors to reduce interest or settle for less than the full amount owed.
- Cut unnecessary expenses:
Small, strategic spending adjustments can free up funds for urgent obligations. Trustees provide budgeting advice to maximize available resources. - Document communication:
Keep records of all correspondence with creditors or institutions. They emphasize accountability, ensuring any agreements or negotiations are properly documented and legally recognized. - Plan for long-term stability:
Beyond immediate obligations, trustees help develop strategies to prevent similar stress next year, including debt management GTA approaches, budgeting, and periodic reviews.
Key takeaway: Working with a Licensed Insolvency Trustee ensures your approach is proactive, realistic, and designed to regain control—not just react to deadlines. Even last-minute action can lead to positive outcomes with structured guidance.
Preventing Future Stress
Once immediate obligations are addressed, planning ahead is essential to avoid repeated pressure next year. Consider these steps:
- Track all balances and due dates to prevent surprises.
- Maintain an emergency fund to cover unexpected obligations.
- Explore ongoing debt management GTA strategies to reduce outstanding balances over time.
- Schedule regular check-ins with a trustee to reassess your financial plan.
Proactive planning transforms stressful periods into manageable cycles, reducing anxiety and improving overall financial well-being.
The Role of Licensed Insolvency Trustees
LITs play a critical role in helping individuals navigate financial challenges, particularly as deadlines approach. As federally regulated professionals, trustees can assess your obligations, explain options, and create strategies that are both practical and legally compliant. Working with an insolvency professional ensures you have expert guidance, reducing stress and increasing confidence in your decisions.
Here’s how trustees support Canadians:
- Comprehensive assessment of your finances:
They review all balances, loans, and unpaid bills to provide a complete picture of your situation. High-interest accounts and overlooked obligations are identified for immediate attention. - Clear explanation of options:
Many people are unaware of the available tools to manage obligations. Trustees explain repayment arrangements, consumer proposals, debt consolidation, and negotiated settlements so you can make informed choices. - Negotiating with creditors:
Acting as a neutral intermediary, they can negotiate interest reductions, deferments, or structured settlements, often achieving results that are difficult to obtain independently. - Personalized planning:
Every financial situation is unique. Trustees develop plans that balance immediate obligations with long-term stability, helping you regain control without compromising future financial goals. - Compliance and protection:
Trustees ensure all solutions are fully compliant with Canadian regulations. Proper documentation and protection measures safeguard you from potential legal consequences. - Education and long-term strategies:
Beyond immediate needs, trustees provide budgeting advice, debt management strategies, and preventive measures to reduce future financial stress.
Engaging a trustee is not just about reacting to deadlines—it’s about having a trusted partner who helps you navigate complex situations, regain control, and build lasting financial security.
Conclusion
It’s never truly too late to take steps and regain control, even as the deadline looms. By understanding your obligations, prioritizing urgent balances, and seeking guidance from a Licensed Insolvency Trustee, you can mitigate stress and prevent long-term consequences. If you act now and explore solutions such as credit counselling Toronto or structured repayment arrangements, it’s possible to fix debt before tax deadline and regain peace of mind.
Take Control of Your Finances Before Taxes are Due
We can help you create a personalized plan to manage your balances, address outstanding tax obligations, and regain financial stability before the deadline. Contact an office near you today for a confidential consultation, and let us guide you through your options with expert support.
Should You Use Tax Refund to Pay Off Credit Card Debt?

Every spring, many people ask whether they should use tax refund to pay off credit card debt, or if that money would be better saved for emergencies. As someone who works closely with individuals and families facing financial pressure, I’ve seen this decision go both ways. The right answer depends less on the size of your refund and more on your overall financial stability.
A refund can be an opportunity to reset — but it can also be a temporary fix if the underlying issues aren’t addressed. Let’s walk through how to decide what makes the most sense for your situation.
Why This Decision Matters
During tax refund Canada season, many households receive one of the largest lump sums they’ll see all year. That creates a rare chance to make meaningful financial progress.
If you’re carrying balances with double-digit interest rates, every month those charges compound. When you’re dealing with high-interest debt, even a few thousand dollars applied strategically can reduce long-term costs significantly.
Before making a decision, consider:
- Are you relying on borrowing to cover monthly expenses?
- Do you have any emergency savings?
- Will this payment change your long-term trajectory — or just reduce the balance temporarily?
Thoughtful planning matters more than impulse.
Should I use my tax refund to pay off credit card debt in Canada?
When clients ask me this question, I guide them through a simple evaluation framework rather than giving a yes-or-no answer.
1 Check the Interest Rates
If your balances carry high rates, applying a lump sum gives you a guaranteed return equal to that interest rate.
2 Assess Your Emergency Cushion
If you have no savings, using the entire amount toward balances may leave you vulnerable to re-borrowing.
3 Review Your Cash Flow
Are you consistently paying more than the minimums? Or are balances slowly growing? If income barely covers expenses, the issue may be structural.
4 Evaluate Total Debt Load
If repayment would realistically take five or more years, even with aggressive payments, a refund alone may not solve the problem.
The goal isn’t just to reduce what you owe — it’s to create stability.
The Pros of Using Your Refund to Reduce Balances
Applying your refund toward balances can offer real advantages:
- Lower interest costs immediately
Reducing principal shrinks future interest accumulation. - Improved monthly cash flow
Lower balances may reduce required payments. - Faster progress
Strategic lump sums accelerate common debt repayment strategies. - Psychological relief
Seeing balances decline can reduce financial stress.
For many dealing with credit card debt Canada, this approach makes strong mathematical sense.
The Risks of Using Your Refund This Way
However, it’s not always the right move.
- No emergency safety net
Without savings, one unexpected expense may undo your progress. - Temporary relief
If spending habits or income gaps aren’t addressed, balances may climb again. - Ignoring essential bills
Stabilizing housing and utilities should come first. - Large overall debt load
A lump sum may not meaningfully change long-term sustainability.
In many cases, splitting the refund is more effective than applying it all in one direction.
A Practical Example: Applying Your Refund Strategically
Imagine you receive $3,000.
You owe:
- $8,000 at 19.99%
- $2,000 at 12%
- No emergency savings
A balanced approach could look like:
- $1,000 into an emergency fund
- $2,000 toward the 19.99% balance
This reduces interest exposure while protecting against future setbacks.
Now consider someone who owes $40,000 across multiple accounts and struggles monthly. Applying $3,000 helps temporarily — but may not fix the larger issue. That’s when broader planning becomes important.
Is It Better to Save or Pay Off Credit Card Debt With a Tax Refund?
Mathematically, reducing a 20% interest balance beats earning minimal savings interest.
Practically, having zero savings creates instability.
For many households, a hybrid approach works best:
- Build a modest emergency cushion
- Apply the remainder to the highest-rate balance
- Adjust spending patterns to avoid future reliance on borrowing
This balanced approach reflects the kind of sound personal finance tips Canada professionals often recommend: make steady progress while keeping your financial foundation stable, prioritizing high-interest balances first, maintaining an emergency cushion, and avoiding decisions that could create new financial strain. By combining these steps, you can use a hybrid strategy that applies part of your refund toward debt while setting aside some for savings, giving you both progress and protection.
What Is the Best Way to Use a Tax Refund If I Have Debt in Ontario?
For anyone asking this question, I typically suggest thinking in tiers:
Tier 1: Stabilize
- Bring essential bills current
- Stop collection pressure
- Secure housing and utilities
Tier 2: Protect
- Establish a small emergency reserve
- Prevent new borrowing
Tier 3: Strategically Reduce
- Target highest-rate balances first
- Avoid spreading funds too thin
If you’re unsure which tier applies, speaking with a Licensed Insolvency Trustee Ontario professional can provide clarity. Anyone looking for debt help Toronto can benefit from a confidential consultation to review their options and understand the protections available to them.
When to Seek Professional Advice
Sometimes the real issue isn’t how to allocate a refund — it’s whether the overall debt level is sustainable.
You may want to seek guidance from a LIT if you’re experiencing:
- Persistent collection calls
- Wage garnishment threats
- Minimum payments that barely reduce principal
- Growing balances despite consistent payments
- Ongoing reliance on borrowing for daily living expenses
In these cases, applying a refund may provide short-term relief but not long-term resolution.
A confidential consultation can help you understand your legal options, your protections, and whether a structured solution may be appropriate. Exploring your options does not commit you to any formal proceeding — it simply gives you clarity.
Final Thoughts
A refund can be a powerful financial tool — but it’s not a cure-all. For many people, reducing high-rate balances is a smart move. For others, building stability first may prevent a cycle of repeated borrowing.
The key is making a decision based on your full financial picture rather than acting automatically. If your balances are manageable and you have some savings cushion, it often makes sense to use tax refund to pay off credit card debt thoughtfully and reduce long-term costs. If the numbers still don’t work despite your best efforts, seeking professional guidance can help you move forward with confidence and control.
Take Control of Your Debt Today
Wondering whether your refund should go toward outstanding balances? Don’t wait until debt becomes unmanageable. Schedule a confidential consultation today with a Licensed Insolvency Trustee near you to create a personalized plan that lowers interest, improves cash flow, and puts you back in control of your finances.
How to Handle Lingering Holiday Credit Card Debt – What to Do Before It Gets Worse

The holiday credit card debt struggle is real — and for many, it doesn’t magically disappear when the decorations come down. If you’re still carrying balances into February, March, or even later, you’re not alone. While the joy of the season fades quickly, the financial aftermath can linger for months, quietly accumulating interest and stress.
Whether your spending was intentional or just got out of hand amid the excitement, the good news is that you don’t have to stay stuck. With the right approach, there’s a clear path forward — and it doesn’t involve panic, shame, or ignoring your bank statements.
Why Your January Statement Feels Like a Wake-Up Call
You did your best to stay on budget — but after a few swipes for gifts, travel, or takeout, your January credit card statement arrives… and it’s higher than expected. Sound familiar? That’s the classic post-holiday debt surprise — and it happens to a lot of people.
This kind of holiday spending hangover can last for months. Here’s why:
- Some holiday purchases don’t show up right away
- Charges from December may hit your account in January
- Little extras add up — gifts, food, events, last-minute buys
Then everything lands at once:
- Credit card bills arrive mid-January
- Rent, groceries, and utilities are due at the same time
- There’s not enough cash to pay off the full balance
- Minimum payments feel like your only option
- Interest builds fast — and debt starts to grow
By March, the holiday season is long gone — but the debt is still there. These lingering holiday expenses can:
- Blend into your regular spending
- Be easy to ignore
- Turn into long-term debt if you don’t have a plan
The good news? It’s not too late to turn things around — starting now.
Why Holiday Debt Sticks Around Longer Than Expected
So why does this kind of debt linger for so long?
One of the main reasons credit card debt after holidays sticks around well into spring is the high interest rates that most credit cards carry. If you’re only making minimum payments, it can take years to pay off your balance — even if you stop using the card entirely. Combine that with everyday living expenses, and it becomes easy to lose momentum and fall into a cycle of revolving debt.
High interest credit card debt can be especially dangerous. It grows quickly and eats into your ability to save or invest. If your interest rates are above 19% and you’re only making minimum payments, you’re likely paying far more than you realize — not just in interest, but in missed opportunities to build financial stability.
This is a red flag if:
- You’re unable to make more than minimum payments
- Your balance hasn’t decreased in three months
- You’re using one card to pay off another
If any of this sounds familiar, reach out to a Licensed Insolvency Trustee to explore your options before the situation escalates. They can provide a clear, professional assessment of your financial situation and help you find a sustainable path forward — whether that’s budgeting help, a consumer proposal, or another solution.
Taking Control Before It Spirals
Here’s what you can do now to stop the situation from getting worse — and start moving toward financial clarity.
1. Assess the Damage Honestly
Start by looking at all your credit card balances and making a list. Include the interest rates, minimum payments, and due dates. This simple exercise can feel intimidating, but it’s a necessary first step toward managing credit card debt effectively. When you face the numbers head-on, you can create a plan that’s based in reality, not guesswork.
2. Prioritize High-Interest Accounts
If you’re carrying multiple balances, focus on the one with the high interest credit card debt first. This approach, often called the avalanche method, saves you more money in the long run. Paying extra toward the card with the highest rate while keeping up with minimums on the rest is a smart and strategic move.
3. Review Your Budget (and Make Adjustments)
Look at your current monthly budget. Is there any room to cut back temporarily — on streaming services, takeout, or subscriptions — so you can put that money toward your balances? Making short-term sacrifices now can speed up your progress and reduce stress later.
Even small shifts can make a big difference, and focusing on holiday budget recovery tips can help you realign your spending habits and make smarter choices going forward.
4. Choose a Debt Repayment Strategy That Fits
There’s no one-size-fits-all approach to tackling debt, but the key is consistency. Whether you use the avalanche method, snowball method (paying off the smallest balances first), or a combination, stick to a plan that feels doable. Many financial experts are recommending customized debt payoff strategies 2026 that reflect the evolving economic landscape — emphasizing flexibility, automation, and realistic goals.
If you’re unsure which method to choose, talking to a professional can give you clarity.
5. Avoid the Trap of Emotional Spending
One of the easiest ways to derail your progress is falling back into spending as a coping mechanism. After the holidays, it’s common to feel a dip in mood or motivation — and for some, spending provides a quick (but temporary) boost. Recognizing this pattern is key to recovering from holiday overspending and making healthier financial decisions.
6. Explore Your Relief Options
If you’re struggling to make more than the minimum payments or your debt feels overwhelming, it might be time to consider more structured help. A Licensed Insolvency Trustee (LIT) is a federally regulated professional who can review your full financial picture and explain all your options — including budgeting support, debt consolidation, consumer proposals, or bankruptcy (when necessary).
Unlike for-profit debt settlement companies, LITs are impartial and legally required to give you honest, unbiased advice. If you feel stuck and unsure how to proceed, connecting with one could be the turning point in your journey.
Planning Ahead to Avoid the Same Stress Next Year
Once you’re back on stable ground, the next step is preparation. One of the best ways to prevent lingering holiday expenses in the future is to set up a holiday savings fund throughout the year. Even setting aside a small amount each month can make a major difference when the season rolls around again.
And don’t forget to track your actual spending during the holidays so you can refine your budget for the future. This helps create realistic expectations — and less reliance on credit.
Final Thoughts
Carrying holiday credit card debt beyond January doesn’t mean you’ve failed. Life happens, and the holiday season is designed to encourage spending. What matters now is how you respond. By facing the situation early, using a realistic plan, and getting professional help when needed, you can take control of your finances — and move into the rest of the year with confidence.
Need Support with Holiday Debt?
Struggling with leftover holiday bills or rising credit card interest? A Licensed Insolvency Trustee at Richard Killen & Associates is here to guide you with clarity and compassion. Book your free, confidential consultation today or call us at 1‑888‑545‑5365 to get advice tailored to your needs.
Contact Richard Killen
FREE No Commitment Consultation
Contact us now for a fresh start!
“Serving Toronto & the GTA for over 25 years.”
Recent Blog Posts
- Why More Canadians Are Choosing Consumer Proposals for Debt Relief and Financial Recovery
- Consumer Proposal vs. Bankruptcy in Ontario: How Income and Assets Decide Your Best Route
- Are You Managing Debt or Just Surviving It? 10 Warning Signs It’s Time to Seek Debt Relief Solutions in the GTA
- Borrowing for Home Renovations in the GTA: Questions to Ask Before Taking on More Debt and How an LIT Can Help
- Back-to-School Expenses Are Adding Up: How to Prepare Without Going Into Debt Help Ontario